Episode 137 – The Steward Investor with Don Simmons

Episode 137 – The Steward Investor with Don Simmons

Podcast episode

Episode 137 – The Steward Investor with Don Simmons

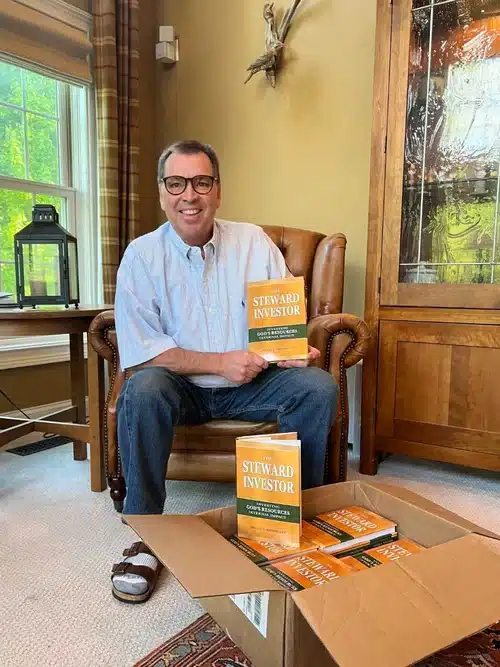
Most investors often start with how to maximize returns and minimize risk. Don Simmons, CFP Professional and Founder and CEO of Simmons Capital Group, believes that Faith Driven Investors should seek to optimize beneficial outcomes instead. 

As a CFP Professional with a degree in counseling and post graduate training as a portfolio asset allocation specialist, Don fuses professional portfolio strategy with investor psychology and behavior. 

Don joins our podcast to talk about his recently released book “The Steward Investor: Investing God’s Resources for Eternal Impact.” Don shares that as Christians, we need to be on the forefront of planting business in economically difficult areas where issues like unemployment and human trafficking prevent human flourishing. Listen in as Don pushes the envelope on the role of Christians as stewards of God’s resources.

To learn more about The Steward Investor, missional investing, and news about Don’s speaking, sign up for his newsletter at https://thestewardinvestor.com/

All opinions expressed on this podcast, including the team and guests, are solely their opinions. Host and guests may maintain positions in the companies and securities discussed. This podcast is for informational purposes only and should not be relied upon as specific investment advice for any individual or organization.

Episode Transcript

Transcription is done by an AI software. While technology is an incredible tool to automate this process, there will be misspellings and typos that might accompany it. Please keep that in mind as you work through it.

John Coleman: Welcome back to the Faith Driven Investor podcast. This is John Coleman and I am here with my partner Luke Roush today, freshly coming off a very good Christian economic forum in Beaver Creek, Colorado. Luke, it’s great to see you. How did you like last week?

Luke Roush: It was great. It’s always a special time of community with folks from here in the U.S. and also around the world. So it’s a reminder of just the scope and scale of God’s church and special things that can occur when we convene and share ideas, knowing that the answers to humanity’s biggest problems don’t come from humanity, but they come from God’s word and fellowship in prayer. So it was a great, great couple of days there in Beaver Creek.

John Coleman: Amen. And it’s a ministry of Crown Financial Services and part of the great work that they do. And I was only introduced to it by you all last year, so it was my first time. And I mean, I just find it really enriching every year. And one of the most enriching parts is Luke mentioned are the great people that you meet there, one of whom is on the podcast today. So we are really privileged to welcome Don Simmons. Don established Simmons Capital Group in 1988 and became one of the first fee based registered investment advisors in upstate New York. He is a legend in the faith driven investment and wealth management space and has recently written a book called The Steward Investor Investing God’s Resources for Eternal Impact. And we’re really privileged to welcome him on the podcast today and talk to him about some of the principles in that book and in the life he’s crafted in investing. So thanks so much, Don, and welcome.

Don Simmons: Thanks, John. Glad to be here.

John Coleman: Well, Don, I want to start with this exciting new book, The Steward Investor. You’ve obviously been quite thoughtful about the topic, but just give us a little bit of background. What is the steward investor and what’s the core thesis of the book?

Don Simmons: Yeah, you know, I’m not really a writer. I guess I’m an accidental author in that this book kind of just spilled out of me last year when I took a leave of absence from work, and it spilled out around really the issue of as Christians, do we really believe what we say we believe? And as a professional money manager, the question that really came to my mind is we frequently say that God owns it all, but there are implications to that, especially in regard to how we invest. So the book really dives into our current understanding of stewardship being primarily about financial competence, which is true whether you’re a Christian or not. And I try to get into more the issue of stewardship being about ownership and being a fiduciary for God who truly owns it all. And that has very direct implications on how we invest. So the book was an attempt to address this issue of investing as a steward, not just making money and then giving it away, but in the making of the money. How do we honor God and bring forth eternal impact in our investing.

John Coleman: And Don, I love how you touched on this idea of stewardship is present even outside of faith driven circles. But certainly for Christians, there are distinctive elements of that. You know, as you looked at the realm of stewardship in the mainstream world and then think about it in the faith driven world, what are some of the similarities with the way that the rest of the world views stewardship? And what do you think is distinctively Christian in our understanding of stewardship?

Don Simmons: Yeah, unfortunately, John, my experience having attended some of the largest impact investment forums in the world, the Global Impact Investing Conference that is held annually in London in the U.K. my primary finding or observation is that Christians are at least a decade or 15 years behind the secular space relative to thinking about investing in ways that accomplish multiple bottom line outcomes, not just a financial return. So how are we similar? We’re similar in the sense that Christians are finally starting to grab a hold of this idea. But we’re still very young relative to the secular world in terms of multiple bottom line impact through investing.

Luke Roush: Don, one of the things that I love about just you’re witnessing in your work is that you haven’t just written about it, you haven’t just talked about it, but you’ve also done it. And one of the first funds that we encountered when we were starting our work a decade ago was some of the work that you guys had done through IBEX. I’d love to have you maybe just speak to that a bit and what that part of your journey has been that kind of guided you to where you are today?

Don Simmons: Yeah, my involvement with them goes back to about 2008 and all I can say is that their work particularly in the least reached unengaged part of the world relative to the Gospel I think is second to none. So much of what I wrote about in the book is from my experience in How can we invest for God’s glory among the least reached, the most impoverished and quite frankly, the most corrupt countries in the world? Unfortunately, I wasn’t able to tell many of the stories that I’ve been involved with simply for security reasons. So I tried to use some of the stories in locations that are not as restricted where security isn’t that critical. But what I learned during my time as the chief operating officer for them was that this kind of investing needs to be done in a way that seeks to optimize a number of different outcomes as opposed to just maximizing financial return. And so optimizing outcomes across both economic, environmental, social and spiritual transformative elements is really critical. And so many times as investors, we start with how do we maximize return and then how can we add to these other things? Well, an optimization approach says all of these pieces have to be addressed simultaneously. And it’s like moving a set of levers or dials. And as you dial one dial one way, it affects the performance in other areas. So optimization is about getting the best outcomes, not the maximum outcome in any individual category, but the best outcomes across all categories. And that’s you know, it’s really exciting when you can do that. And some of the stories that I tell in the book just exemplify the wonderful transformation that’s occurred in communities. And our hope is across entire countries because of the businesses that we’re planting.

Luke Roush: Well, and one of the things that I really appreciated about the IBEX story is the way that you and others in that fund waded into what many folks would probably call the messy middle. Right. It wasn’t philanthropy. It wasn’t even sort of zero interest lending. But it also wasn’t always kind of at market risk adjusted rate of return investing, which there’s flavors of that within FTI as well. And I think that one of the things that IBEX did well is trying to wade into that middle ground of this is work that needs to get done in parts of the world that are quite dark and we want to be able to introduce market mechanisms to how we supply capital, but we want to do it in a way that also maintains focus on non-economic outcomes. So maybe just speak to kind of that and what that journey look like over time.

Don Simmons: Yeah, and we’d love to have this discussion about market like returns or concessionary returns. And I want to be frank that I am a capitalist. I believe in investing. I believe that profit is the lifeblood of a business. But as a follower of Christ, I’ve come to believe that maximizing financial return is not my top priority. And so I believe that it’s appropriate to have funds like sovereigns and others that are participating in the public marketplace with traditional investments seeking high returns in ways that honor Christ. But my book is really challenging to the Body of Christ because most of us want to migrate toward the financial return because that benefits ourselves. When I look at managing money for God, I have to think about, well, what are his objectives? You know, he commands us to go and make disciples to the ends of the earth. He calls us to be the salt and light of the Gospel and to bring forth the great commandment, loving our neighbor as ourselves. And many of those times, you can’t do that in these difficult places and start with a financial return mindset. In fact, the kind of investing that we do as a professional, I would say you can’t possibly get the appropriate return to justify the level of risk that we’re taking. So if that’s the metric that I start with, we might as well just abandon it. And I simply disagree that as Christians, we need to be in the marketplace, we need to be planting businesses in very difficult locations. And often we have to be making decisions to plant businesses where they may not likely succeed in the way that we normally think, because the infrastructure isn’t there, the trained workforce isn’t there, there isn’t reliable electricity or Internet. There’s high corruption. It’s hard to start with a financial return mindset and be successful in those environments unless your priorities are how do we reduce unemployment from 80% down to 20%? How do we care for those who’ve been exploited because of human trafficking and making sure that they have jobs that can support their family without returning to that enslavement that they had been a part of? These are difficult questions, but I want to push the envelope with Christians to think that part of our role as stewards is to address those issues. And it’s not about donations being sacred and business being secular. We can address those concerns in the making of the money, in the way that we invest. I think in a way that’s more impactful than just through donations.

Luke Roush: I think it’s a great push on. It’s a good challenge for us and for just the entire movement. So I’m grateful for you pushing on that.

John Coleman: And Don, I’m a story guy, so I wanted to touch on, you mentioned there are a lot of great stories in the book where you’ve seen this in action. I would love to hear one of those stories, if you don’t mind, to put color around the concepts that you’re talking about, where you just seen the ability to create a company or some other type of asset in these places that you think has had a remarkable impact.

Don Simmons: Yeah, and this is one of the stories that’s in the book that perhaps may be my favorite because of the involvement of my own daughters in this story. We had made an investment in a project in Nepal, what would be termed a freedom business, which is a business that is specifically set up in order to help provide jobs for those who’ve been exploited because of human trafficking. And so I took two of my girls to Nepal with me to visit a handful of freedom businesses in Kathmandu and get a feel for this tragic problem. After visiting a number of freedom businesses. We took a hiking trek up into the mountains where human trafficking had been most prevalent in this area. And it was about the third day of trekking after a six hour jeep drive across muddy roads that you thought you were going to fall off of the cliff. But then we started hiking and on the third day, my 18 year old daughter, Kristie, looked at me and said, dad, why are there no girls? And before she finished the word girls, she looked at me and said, Oh, those businesses that we visited in Kathmandu are for the girls that are no longer here, because in those small villages there were no teenage girls. There were no girls over the age of about seven because they had all been sold into human trafficking. And it wasn’t until one of the last days that we had a deeper conversation. We had been staying at what are called homestays. They’re like a little youth hostel in each village, and these youth hostels had been set up by a very wise business group for the specific purpose of helping to create an industry among these impoverished villages where trekkers could stay at these homestays and it would generate revenue, locals could sell chickens to the tourists or candy or water, and it created really a vibrant economy in these villages. And on the last day, we stayed in one homestay and there was a girl who was 14 years old. She was the first teenage girl in these villages in many, many years. And it’s because her family owned a homestay. And so for me and the impact on my daughter, to see that and also to ask myself if I lived there, would I have sold my daughter because there was no other way to provide for the rest of my family. So it’s just wonderful to see how business in that case has almost eradicated the human trafficking in that part of the country in about a decade of work. Just an incredible story.

John Coleman: Wow. Don. That is remarkably powerful. I was reminded of something similar, not quite as intense. I was able to take my oldest son, my nine year old, on a mission trip recently, his first in the developing world. And it’s just so powerful to be exposed or in my case, to be re-exposed to the way that other people have to live and to really put yourselves in their seats and to understand how difficult some of these choices are and to understand how deep the need is. To serve others in these parts of the world. And the idea that you can do that not just through nonprofits or through charity or through missions, but also through building redemptive enterprises in these countries, I think is inspiring. I know we want to pivot a little bit to how you advise people on this and maybe to kick that off. It can be overwhelming looking at opportunities like you just described for the average investor who’s in a 6040 public portfolio to think, how do I get into this? How do I start making an impact? You know, as you talk to folks and they want to do more of what you just described, what are the first steps that you often advise people on is they want to deepen the impact that they can have with their financial stewardship.

Don Simmons: I think the first question is whether a Christian’s portfolio should look any different from a non-Christians portfolio. If we’ve come to believe that stewardship is about financial competence, we may think the answer to that is no. We should do the very best that we can to make as much money as we can so that we can give money away. And I simply have come to disagree with that. And I manage several hundred million dollars for people in traditionally traded investments. Most of my clients are not Christians, but when I manage my own money and at least ask the questions of other Christians, how should my portfolio differ? As a follower of Christ, I have to either consider that maybe there should be some screening on my traditional investments so that my investments align with my moral and Christian values. But I have never been one who looks at my faith as do’s and don’ts, so I’d rather not be one who just excludes things, because that’s what my faith says. I’d rather be proactive. I call it proactive values investing. PVI How do we find investments that clearly align with our values that are seeking great commission outcomes, that are seeking to disciple people in the Muslim, Hindu and Buddhist part of the world? That’s a very different approach, and it requires a comprehensive management of all of the portfolio so that you can balance the risk and return with traditional investments to offset perhaps the higher risk and lower returns of these missional kinds of investments. And it’s yeah, it’s not easy. I think that people will need a guide for that. Unfortunately, the financial services world is one where regulation prevents most financial advisors from even talking about these kinds of things because their private placement, non publicly traded investments. And if you operate within a broker dealer FINRA regulated system, you can’t talk about a private placement investment in Ethiopia because your broker dealer doesn’t approve that. So my hope over the next few years is to be a voice into the financial services community. How do we release financial planners to provide this kind of advice? And that’s where I hope that FDI, Kingdom Advisors and Crown and others can start to address the compliance and regulatory issues and just the structural issues of financial advisor firms so that they can provide. That’s my publisher, really. Before publishing the book, when he had the manuscript, he said, Don, you’ve persuaded me. I need to invest differently, but who’s going to be a guide? And at that time I said, Well, there’s really not a guide. And over the course of a few months, I was persuaded by the Lord that somebody needed to set up an advisory firm to do that. So we’ve just gotten FCC approval, and we’re fully in business now to help people manage their money holistically, to include a comprehensive, risk adjusted portfolio that aligns with people’s values and simultaneously brings in these unique private placement investments that proactively bring forth missional and redemptive outcomes.

Luke Roush: So for the financial advisors who are listeners to the podcast and are likely very interested in this topic, what are the on ramps for them to be able to engage with you or be able to? You know, we talk a lot about how do we leave the ladder down for others? So like, what does it look like for you with your work to either leave the ladder down for others or to be able to engage with advisors who are interested in this space but aren’t really sure kind of what the first three or four steps looks like.

Don Simmons: Yeah, that’s a tough question, Luke. I think FDI can play a big part in that, that perhaps we may need to have a discussion group that’s specifically on this topic for advisors that gets beyond BRI, which is wonderful, but how do we start to engage at a deeper level of proactive values investing? Certainly they can connect with me at my website Steward Advisors Group dot com or the book web site, the steward advisor dot com. Mark Weston in Birmingham has an R.I.A. that is called Eversource. They are also starting to dip their toe into the water. Rachel McDonough has been involved with FDI and Kingdom Advisors. She’s got a business set up to help to train and coach advisors in this area. So the good news is, compared to five years ago, I would have said there was no advisors doing this kind of stuff. Now I can say, well, there’s three names that are starting to explore this, and I would hope that in ten years we have 100 RIA firms that are doing this.

John Coleman: Don That’s awesome. And it’s an encouragement and it mirrors what we’re seeing where the number of investment managers has dramatically expanded in public and private markets over the course of the last five or ten years. And the quality of those investment managers is continued to improve as well. Their ability to access great deals, to navigate those well, to be a good fiduciary for their clients. And I think that explosion of interest in faith driven investing and the ability to action it through great advisors and investment managers is really essential to move the industry forward. I’ve seen what you’ve seen. I came out of the mainstream investing world and you know, I would say the mainstream values investing world has at least a 20 to 30 year jump on Faith Driven Investing right now, I mean, it’s huge, but there’s a lot we can learn from that, right? And there’s a lot of ways in which we can catch up as we’re navigating a distinctively Christian approach to those topics. I think, you know, one thing that strikes me as I listen to you, Don, if we can back up maybe and focus a little bit more on you, is talking to you that you’re the kind of person who often becomes a pastor or a missionary who has a deep and deep passion for this. And yet you became not only a business person, but a financial person, which many people view is very far from the mission field. Talk to us a little bit about your history and just how you came to this field and came to believe it was your calling.

Don Simmons: Oh, you know, it really starts in college. I was a computer science major, so I kind of am a math geek. But by my junior year, I had determined that I didn’t want to sit behind a computer debugging program, so I needed a social outlet. So I ended up with a double major in computer science and psychology counseling, just the opposite figure that’s as far away from analytics as you can get. But as it turns out, being a financial advisor requires both. You have to be really good at the mathematics, and then you need to be able to communicate that with people and ways that they can understand. After college and I was in ministry, I worked for several years as an area director for Young Life, basically, which is an outreach to high school students, not a church youth group leader, but just to the kids that are at the high school. And when I look at my career now, the last 15 years, being involved in that business as Mission BAM or B for T business, for transformation movement. For those of you who understand young life, I just say this is just young life with business people. It’s the incarnation of ministry in the marketplace. It’s going to where people are. And so, you know, what I love about financial services and business, if we dispel the idea of a sacred secular divide, there’s no sacred or secular vocation. And we also have to remember that donations are not sacred and investments are not secular, that our investments are just as sacred as the donations that we make when we’re managing it all as God’s fiduciary. In the book, I call it Gods oikonomos. That’s the Greek word for household manager. A fiduciary or an oikonomos owns nothing that they manage. And personally, as I understand my role as God’s steward, I own nothing. Therefore, everything should be managed for His glory and to point people to him.

John Coleman: That’s awesome. Don, and you know, in that context, I also know you’re an engaged husband and father of four. I think I have four as well. And you do act. To fully participate in service offerings around the world. Talk to us a little bit more about how your faith plays into just your role as a husband and father, and also just how you, outside of your core business, seek to engage your faith in service.

Don Simmons: Yeah, I have a hard time drawing lines between personal and business, hence the reason that once my kids are 16, they’re kind of on the rotation to go on these adventures with me to strange parts of the world, you know? To answer your question, John, I just think that everything that I do is in service to the Lord. So it’s critical that I have a number one responsibility to my family and raising them up to understand matters of faith. Of course, as they become adults, they have to make their own decisions. But I want to plant as many seeds into them while they’re young, not just by sending them to church or Sunday school or camp, but for them to see in real life. How does this play itself out as a business owner, as a dad, as a husband? You know, my faith, just like I started that conversation, if I really believe what I say I believe, then God has to control and influence and invade every aspect of my life. So to me, it’s hard to draw a line between the two. It all kind of melds together.

John Coleman: That’s awesome. Don I think what we might do now is pivot to a very fun part of the program, which we call the Lightning Round. So we have explored a bunch of in-depth topics. Now we want to try and get your 30 to 60 second responses to a couple of fun topics. And I am going to start with a fun little fact that I learned about you in preparing for this show. Apparently you like to fly a 1948 Aeronca sedan float plane in 60 seconds. How the heck did you start driving a float plane? And what’s that like?

Don Simmons: I grew up on a lake, so I love water and boats and swimming. When I was probably about 30, 35, I got an interest in flying very quickly, got my private pilot’s license, and in order to stay current, you have to take extra classes every other year. My first class was flying a seaplane and I fell in love with it because of my love for boating and my love for flying. The problem is, is that you can’t rent sea planes. So if I was ever going to really enjoy that passion, I was going to have to buy a seaplane. And a 1948 plane is less expensive than most people’s car. So that’s how I ended up with Aeronca sedan, which was the float claim to have. If you lived in Alaska in the 1940. it can haul a lot of people and it’s got big windows, so it’s great for sightseeing.

John Coleman: As a financial person, before Luke takes the next question, I am struggling to think what the underwriting for renters insurance on a 1948 Sea plan would look like. So I can’t imagine that the sea plane renting business is not very active.

Don Simmons: That’s why you can’t rent them. You either need to buy them, usually in partnership with other people. So I bought this with a friend who restores airplanes and he completely restored it. It’s. It’s beautiful.

Luke Roush: Wow, that’s awesome. I want to pivot it over to just mentoring and just the importance of it’s something that you’ve talked about, love to understand your quick take on why this should not just be a priority for some but should be a priority for all.

Don Simmons: Yeah. I mean, mentoring younger people has always been a passion of mine, but specifically starting this new business at age 59, I’m thinking very differently than I did when I started the business at 23 in that I’m trying to identify successors, maybe people who can take the reins of this business in five years or ten years whenever the Lord has me start to slow down. So it’s not just in terms of business that I want to mentor people, but it seems like most of the conversations I have today with young folks who are are millennials or Gen Z. They’re already passionate about this holistic integrating faith into everything, but they need the wisdom and experience of those of us who have gone before that. So it’s not just the passions, but how do you tie that with the reality and you only get that with experience.

John Coleman: So, Don, I’m going to give you one last lightning round question. You’re a well-traveled person, often to relatively off the grid places. What’s been your favorite place that you’ve visited and why?

Don Simmons: Yeah, I think my favorite. Is Kyrgyzstan simply because of the deep friendships that I made there. And it is a country that is just spectacular with beauty. I was mentoring a printing publishing company there for many years from 2010 when there was a overthrow of the government for maybe the next ten years. And we would have our board meetings as camping trips out to the mountains between Kyrgyzstan and Kazakhstan. Frequently we’d have our campsite and campfires at about 10,000 feet of elevation. Just a spectacular, spectacular country. And the people are wonderful.

John Coleman: Yeah, I had a chance to spend a little bit of time in Central Asia, in Afghanistan, in Mazar I Sharif, which is up in the northern part of the country. And it is I mean, Central Asia is beautiful and desolate and different and everything you could describe and I know all the countries are quite different as well, but it’s one of those places that most people haven’t had the chance to be. And it’s one that I hope people get to at some point, because it’s often overlooked.

Luke Roush: And I was actually always curious where the name IBEX from IBEX Fund originally came from. But now I know because that’s actually where you find IBEX is above eight or 9000 feet in Kyrgyzstan, Tajikistan, Afghanistan. So that’s I assume that you saw them when you were over there.

Don Simmons: Oh, absolutely. And a great icon for a great business, thriving in difficult places.

Luke Roush: Oh, yeah. That’s awesome. Hey, one last question for you. We always like to wrap each podcast with some part of where God’s word is speaking to you lately. And so how would you just speak to what God has taught you lately through his word.

Don Simmons: You know, I wrote about this in the book about the Lord’s Prayer and specifically about give us this day, our daily bread. You know, the longer that we’re in our careers, especially one who’s a financial service guy, we should typically be approaching age 60 at a point of financial independence. And one of the things that I’ve learned, probably because of the involvement in so many businesses that struggle, is that I pray every day now for my daily bread, not just for my family’s needs, but for the daily bread, for the businesses that I’m involved with that are struggling. And my wife, Amy and I have made a commitment for the last 15 years that we need to live in the same level of faith as those who are dependent on us for financial support, either through donations or by the investments that we make in their business. We heard one wise man many years ago talk about matters of faith and that when you’re in your twenties, it may be a lot to give $1,000 to something that requires a lot of faith. But for those of us who are farther down the journey, we need to have the same level of faith. It probably just means we need to add more zeros to those things that we’re praying about. So to answer your question, Luke, praying today for the daily bread for myself and those that we are partnered with, because I believe God has provided enough resources in the world, they’re just not properly distributed. And in America we tend to hoard them for our own needs so that we think we can be financially independent, when in fact we really need to be dependent on God on our nest eggs. Hmm.

Luke Roush: Don, we’re grateful for you sharing wisdom with us and our listeners today. We’re grateful for the gift that you’ve given to a community with the book steward investor, and I look forward to reading it in more detail in the coming months. It just arrived last week and so excited to get into it and grateful for your example in a really positive and redemptive direction over the last decade plus. So we appreciate you.

Don Simmons: Thanks. Luke and John, this has been a lot of fun.
Subscribe to the newsletter

Stay Connected
to the Movement

We know that as an Entrepreneur, your most valuable asset is time. So each month we take the very best of the podcast, the blog and all the news, resources, and upcoming events happening across the space and bring it to you.

Episode 138 – Passing Your Family Business Down with Phil Clemens

Episode 138 – Passing Your Family Business Down with Phil Clemens

Podcast episode

Episode 138 – Passing Your Family Business Down with Phil Clemens

Phil Clemens spent 52 years on the payroll of the Clemens Food Group, a sixth-generation family-owned business providing quality pork products to the U.S. The business is now the 5th largest producer of pork in the U.S. with annual sales in excess of $1 billion. 

As the former chairman of the Clemens Family Corporation, Phil spent 14 years developing a succession plan for when he retired. Phil joins the Faith Driven Investor Podcast today to talk about the importance of legacy and how a family business can successfully and effectively be passed to the next generation.

Want to dig into more content with other like-minded investors? 

We created the Faith Driven Investor Foundation Video Series for you to discover how you can bring glory to God through your investments. Groups start in January 2023. Join one at https://www.faithdriveninvestor.org/foundation-series.

All opinions expressed on this podcast, including the team and guests, are solely their opinions. Host and guests may maintain positions in the companies and securities discussed. This podcast is for informational purposes only and should not be relied upon as specific investment advice for any individual or organization.

Episode Transcript

Transcription is done by an AI software. While technology is an incredible tool to automate this process, there will be misspellings and typos that might accompany it. Please keep that in mind as you work through it.

John Coleman: Welcome back to the Faith Driven Investor podcast. Today we have a very, very special session as we are pleased to welcome Phil Clemens. Phil was formerly the CEO of his family business, the Clemmens Food Group, which had more than 3500 team members around the world. He has worked in a variety of businesses, served on a number of boards, and I’ll say also is just known in the community as someone who’s incredibly supportive of others. He’s constantly looking to invest in others and just has a genuine kingdom mindset. And we’re really excited to learn from him today, both about his approach to investment and to thinking about faith led businesses and also the way in which he’s approached family legacy, family business and encouraging other families that are in entrepreneurship and running businesses. So, Phil, thanks so much and welcome to the show today.

Phil Clemens: Glad to be here.

John Coleman: Well, Phil why don’t we get started just with a brief biography. We reviewed a few of the details just now, but who are you and where do you come from and what is your experience been over the course of the last few years?

Phil Clemens: Okay. Well, my parents were less and Kay Clemens. My dad was in the business before me. I’m married to Linda. Next year, we celebrate 50 years in marriage. We have three daughters. Our oldest daughter actually works in the business. Our second oldest daughter is a missionary. She’s married to Paul College there with Mission Aviation Fellowship, and they were in Indonesia for 12 years and now they work in member care and they have four sons. And then my youngest daughter Ruth is married to Brant College. She was a schoolteacher. She’s a stay at home mom now and she has three boys. So we raised three girls and now we have seven grandsons.

John Coleman: That is a houseful, I bet, at holidays.

Phil Clemens: It is. It is. It’s fun.

John Coleman: That’s awesome. Phil and tell me you’ve had a pretty long history in your family business. Tell us a bit more about that, how it started and how you work through the ranks there.

Phil Clemens: Well, when my parents got married, they lived right next to the business. And at the age of ten, I was a middle son. I had two other brothers, one older, one younger. My parents gave us the option to go to work at the family business or do more chores around the house, both for the same pay nothing. So I decided I’d go to work at the family business. So the first two years have been get paid. At age 12, I got on the payroll at $0.75 an hour and work part time up through all of high school till into college. And then I began full time while I was in college. And when I got out of college, I actually asked to be interviewed with the business to see if I wanted to stay there. I didn’t want to feel that I was entitled to a job, that it was something I wanted to look and see. Did they want to hire me and did I want to work there? And I actually had interviewed quite a few places and the company business was the lowest pay, but the greatest challenge. So I went to work for the family business.

John Coleman: Well, they got a discount and they hired well, Phil, because you eventually went on to be CEO and chairman, although you stepped out of that role in 2015. And I want to pivot in a moment because I know you’ve been very thoughtful about investments and the impact of building faith aligned businesses, but just give us a brief overview of what you’ve been doing since 2015 as we circle back to that later.

Phil Clemens: Well, you know, I was always taught that you spend your first 20 or 25 years learning the next 40 or 50 years earning and your final years in returning. So I’ve been in the returning phase and for the last seven years I’ve been involved with about 12 or 13 boards. Some are faith based, others are family businesses and trying to help them. Some I actually go on boards where I become salt and light and try to share my testimony with others in business. So it’s been a real time of returning to others.

John Coleman: That’s awesome. Phil And we’re going to circle back a lot to this concept of family business because it’s something you’ve been really thoughtful about, both in your own business as well as those of others. Before we do, though, you know, this is the Faith Driven Investor podcast and we think a lot about the ways in which people can integrate their faith into the way that they invest. Would you mind talking for a moment just how you think about that topic?

Phil Clemens: Yeah, I think, you know, as a business person, we invest our time, our talent and our treasure. And some of it’s the capital investing financial capital. And how do we get a return on that and how do we become a good steward of what God has given us? And one of the things we have done as a company is we believe in tithing our profits and not only tithing our profits, but we share about one third of our profits with our team members. We believe it’s really important for the team that helps to generate the profit, that they get a fair amount of that profit. And so we encourage the company to continue to invest globally, but also invest back in our community and back into our people. We think that’s really, really important. And from a stewardship standpoint, I think some day God’s going to ask us, what did you do with what I gave you? And we’ll look at and even give answers of how we actually invested back in our community and to our people.

John Coleman: Phil that’s awesome. And, you know, one of the things you brought up, you’re describing a bit what some people would call stakeholder capitalism, right? Where you’re thinking about shareholders is one of many groups that you’re considering, whether it be the community employees, in this case, your own faith in God. How do you balance those tensions between the economic returns of the business and these other stakeholders that you want to account for?

Phil Clemens: Well, we think it’s really important that we actually put ourselves last. We believe putting God first, putting our employees second, and then the shareholders come last. You know, a lot of businesses do just the opposite. They say shareholders get the first amount and then we give some to our employees and maybe some to charity. We believe it’s just the opposite model that God has told us. If we put him first, he will bless us. And I think he blesses us to be a blessing to others.

John Coleman: That’s awesome Phil. And as you think about the way that that’s impacted your employees, you know, one of the things we observe is that we have a conviction at the firm that I work at, that healthy cultures create competitive advantage, that investments in people actually do have a really positive return on investments and that caring for people will actually lead to greater economic success for the business. Have you seen that in your own business and how has that manifested for employees? What does it look like for you to invest in employees?

Phil Clemens: Well, yes, we have absolutely seen it. And, you know, you don’t do it to get the economic benefit. That’s just a consequence of God allows because of a choice you’ve made. And to me, when you invest in your employees, I can give you a story after story of how we’ve blessed our employees from time to time. And oftentimes when we bless them, we ask them, Is there somebody that you should be blessing because you’ve been blessed? And I will tell you, there’s times when we’ve give significant bonuses to our team members, and I hear stories of how they turned around and gave their entire bonus away to somebody else who was hurting because they had a chance to bless somebody else because they have been blessed.

John Coleman: Wow, isn’t that amazing? And that’s such a great reflection of scripture and really the core element of the great commandment, right to love God and love others. And you see that as you express that, that it makes it even easier for others to express that in the way that they live. I want to pivot now to the specifics of a family business, which is obviously quite a unique context, as opposed to just a general business. What do you think are the unique challenges of running a family business?

Phil Clemens: Well, every family business has three unique circles where other businesses only have two circles. In a normal business, you have the business circle and you have the ownership circle. In a family business, you add one other circle, and that’s the family circle. And what’s really critical is you need to know what hat you’re wearing. You know when to wear a family hat, when do you wear an ownership hat and where do you wear the employee hat? And unfortunately, many family businesses, actually, they only wear one hat. They wear a family hat, and that trumps everything. But unfortunately, when you enmesh those together, it ends up with a lot of confusion to family, to employees, and to others and actually to yourself.

John Coleman: One, it can make it a bit more personal, I would imagine, to, you know, with in a typical business context, we obviously try and express love for those with whom we work, but they’re not actually family. Whereas, you know, the potential for hurt feelings or for things to be taken personally in a family business seem to be much higher. How have you navigated that over time, especially as you walk that balance between owner, employee and family member?

Phil Clemens: Well, I would tell you that in my years of employment, I’ve probably have terminated at least a dozen of our family members. And I have to realize when I terminating them, when I was wearing the boss hat and as soon as I terminated them, I immediately took off the boss hat and put on the family hat because they’re still a family member. And how do I relate to them as we go through it? And one of the things that I have a rule that I set up is what I call my communion rule. And that means I may terminate you as an employee, but if I come to church with you on Sunday and we have communion, if I can’t take communion with you, I’ve done something wrong. While you may not want to take me with me, but that’s okay if I can’t have communion with you. I’ve done something wrong and I need to go and confess something to you.

John Coleman: Wow. That’s an amazing heart check, Phil. I’ve never actually heard someone describe that. You know, that would be useful metric, I think interacting with anyone, if you’ve treated anyone in a way, you feel like you can’t take communion with them. It’s probably a gut check that you’ve done something wrong in that relationship.

Phil Clemens: Yeah. And oftentimes those damage relationship and they damage every one of the circles. They damage family relationships, the ownership relationship and the business relationship.

John Coleman: You know, one of the other unique elements of a family business is that the shareholders or owners of the business aren’t some disembodied third party or large group of investors. Employees see the family every day, and that probably creates unique opportunities and tensions. How do you make sure the family and the employee base are really aligned?

Phil Clemens: Well, I should tell you that our family is really large. Let me just give you a little bit of history from our family. My grandparents had 14 children. For those children died before their first birthday. So they raised ten children, five boys and five girls. So living in our family today from my grandparents are about 850 to 900 family members.

John Coleman: Wow.

Phil Clemens: 380 of them are shareholders of our company. So less than half of the family are actually shareholders. 23 of those actually work in the business. So how do the 23 relate to all of our team members? Is they don’t relate to the entire family. But, you know, from time to time, we eventually invite the entire family to be with our shareholder base because we want them to see our team members as part of the family.

John Coleman: Phil I had no idea how big your family was actually in more than 300 shareholders. That is remarkably complex for a family business.

Phil Clemens: When our shareholders actually go right now from the second generation to the sixth generation.

John Coleman: Unreal. What does it look like to have a shareholder meeting just tactically? How do you think about that and what are the conversations look like?

Phil Clemens: Well, we try to really focus on the business, not focus on the family, but we also look and say, what does it mean as owners? How do we look at this business and again, really have them understand a mindset that they’re an owner, but they really only have ownership. They don’t actually act as an owner. So it’s a very different mindset. As an owner, I can go do with it whatever we want. Well, if we really believe God owns this business, He owns that business and we just have ownership in it and we’re stewards in it. So we really want our shareholders to see the business as a stewardship business, but also when they get shares given to them from their parents or grandparents, that they really see this as an heirloom, something that they can take care of and gain a value to pass to the next generations.

John Coleman: So there’s a real cultural element to it, just the mindset that your family has about its ownership stake in the business, and then there must be kind of a tactical component to it as well. So do you have almost like an executive board within that shareholder base that really leads most of the day to day decisions in the business? Or how do you think about that and how is that group selected from such a large group of family members?

Phil Clemens: Well, what’s really interesting, we do have something we call the Clemens Family Owners Board. That’s a group that speaks for all of our shareholders to speak as one voice. We actually have a board of directors to oversee the business, and it’s always been our intention to have the majority of our board members be independent directors and only have a few family members on the board. We want to have the board held very high accountability to our management team.

John Coleman: I mean, that’s best practice. Even if you think about public companies where you’re generating real independence for the board, that’s going to feel risky to some family members. Though I would imagine appointing independents, how do you select those folks and how do you get the confidence of the family as you’re picking those people?

Phil Clemens: Well, we have real criteria. We look at we want to make sure that they are going to be in align and embrace our mission. Now, our mission of our company is very unusual. It says this We aspire to operate in a way that honors the Lord Jesus Christ as demonstrated through ethics, integrity and stewardship. So when we go and interview potential board members. We want to say we have a very unique mission. And we’re going to ask, can you embrace this as we go forward, because it clearly is not politically correct in the 21st century?

John Coleman: Yeah, that’s a very distinctive mission. I mean, we I often say as I write about things like purpose, culture and mission, that a really good culture and a really good mission will turn off as many people as it excites. Right, that people

Phil Clemens: It does.

John Coleman: Know they want to join and no, they don’t want to join by looking at it. And if it’s something that’s kind of so broadly acceptable that everyone kind of thinks they want to join or be part of it, it’s probably not very distinctive right now. And so what I love about that is you’re so distinctive about the values of the business and so clear with everyone who joins about the expectations coming into the business.

Phil Clemens: And what we do, we actually take a look at that. Our core values is our foundation. And our core values are ethics, integrity and stewardship, which is right in our mission statement. But we also give them very simple definitions ethics. I’ll do the right thing. Integrity, I’ll do what I say. Stewardship, I’ll build a foundation for the future. From that core value, we build our mission and therefore we add the Lord Jesus Christ into it because that’s who we’re serving. And we want people to know that we’re going to be held to a higher standard because of having him at our mission statement. We don’t try to wear it on our sleeves as a banner. It’s just this is who we’re going to be accountable to.

John Coleman: Well, it’s in some ways, it is a great accountability mechanism. I know I work in a business that has got explicitly as part of our mission. And I was in a debate recently with some of our team members, and one of the team members said, you know, are you comfortable with this decision with people holding us to a higher standard and think of us as a representation of Christians in this area? And it was kind of a dagger like you really do have to hold yourself to an exceptionally high standard, probably higher than most people would, because you feel the burden of reflecting on your creator and of your savior. And that’s a higher burden, I think, than any fiduciary burden that exists.

Phil Clemens: Absolutely. But let me just tell you one story real quick about I was teaching a leadership class at our company, and part of it was about our mission statement and one of our team members who is new out of college, a real potential rising star. So the reason I came to work for this company is because of your mission statement. And so I asked the question, are you a Christ follower? She said, Absolutely not. She said, When I was growing up, I was raised Catholic. When I went to college, I threw away all my religious beliefs. But when I came out and I saw what this mission statement was, I was attract this company. And I said, so let me ask you this. How do you think you honor Jesus Christ? The Lord Jesus Christ. That’s very easy. She goes, She said, We have our core values. The first is ethics. I’ll do the right thing. If I come to work every day and I’m doing the right thing, I think that’s going to honor Jesus Christ. If I come and I keep my promises with integrity, I’m going to honor Jesus Christ. And if I do stewardship, which I build a foundation for the future, I don’t have a short term mindset of a long term mindset. I think that honors Jesus Christ. And I believe honoring Jesus Christ is a good thing to do. Even though I am not a Christian or a Christ follower. I just think that’s something that’s really amazing. And I call this person a pre-Christian. She’s moving towards it.

John Coleman: Isn’t that amazing? You it shows not to go off in too much of a tangent, but it just shows what a powerful figure Jesus was that even in the midst of cultural debates about Christianity and different perspectives on that, I think the figure of Jesus and what Jesus stood for so very clearly in terms of loving others, in terms of caring for others, in terms of acting with integrity, is almost unassailable. And people see that and they’re drawn to it. I mean, that’s nothing original to say, but you really are drawn to it and it’s such a good reminder of that. When we talk a little bit about, you know, you’ve mentioned the ways you interacted with employees, etc.. How long were you CEO of the business? Remind me.

Phil Clemens: I was CEO from 1994 until I retired in 2015.

John Coleman: Wow. An incredibly long tenure. And what I’ve heard is you actually spent a ton of time on succession planning within that. And again, with the complexity of family ownership and presumably family leadership in the business, what does succession planning look like in a family owned business like this versus, you know, a publicly traded business or some other form?

Phil Clemens: Well, you have to be very intentional in succession planning. Our owners have come along and said we prefer to have a qualified family member leading this business. Now, if we don’t have a qualified family member, we won’t have the most qualified person in the business deleted family or not. So as I was looking towards my own retirement, I wanted to make sure that I could take to our independent board between three and five highly qualified family members. So I went through a process. It took almost 15 years of meeting with anybody who wanted to see what leadership was all about. And I met with them on a quarterly basis where they read a book. I talked to something I called Lessons in Leadership. What do leaders have to know? How do you really build your character? For instance, I spent a lot of time on, you know, about the cost of leadership. So often times people want to understand all the benefits of leadership and what are all the perks that come with it. I want to tell you what this if you don’t understand the cost, you’ll never appreciate the benefits. And I want to let them know that there’s a big cost to leadership. And if you’re not called to be there, you won’t be effective. And are you really called to be a leader and challenge them? Don’t just try to get a job that you think is going to be one that I can brag about and say, here’s what I’ve done, but one that you’re really saying, this is what I’m called to do because it’s not going to be easy.

John Coleman: That’s remarkable, Phil. And, you know, as you’ve put that challenge before people. How have they responded and what is that mentorship of the next generation look like over a period that long?

Phil Clemens: I think if you go back to the Old Testament, the Old Testament talks about telling the story and be able to tell it wherever you’re going. And I think it’s really important, as you mentor, the next generation. They don’t understand all the struggles that happened in the early days. They don’t understand how we got to be where we are today. And they need to know what are the struggles? What are the things we did right? I think one of the things with family business is you’ve got to tell the story, warts and all. Tell them what you did wrong and how did you learn from it. And again, let them know that you’re not perfect, that you’ve stumbled, you’ve done some things wrong. But here’s how we’ve corrected it and here’s how we go forward in doing that. And that’s really part of the whole mentoring process. And to sit down and say, Here’s lessons I’ve learned. I’ll tell you where I screwed up and stuff that I didn’t do right. And I want to prevent you from going down that trail.

John Coleman: Well, you’re describing a really thoughtful succession process, but also a complex one. And you’ve got a complex ownership structure. As you mentioned. You’ve got this whole third circle of accountability versus a typical business, and the business has been around for a very long time. Over that time, you must have gotten pressure to sell the business, either from parties coming in to try and buy the business or from family members who thought it might be time. Why has it been so important for you to maintain that family ownership structure?

Phil Clemens: Well, we actually look at this as being our legacy, and the legacy is an heirloom. And, you know, any time you receive an heirloom from the prior generation, you can do one or three things with it. You can put it on the mantle or put it there for everybody to look at and just see what it’s like. The other thing is you can say, well, this heirloom doesn’t mean a whole lot to me. Let me see if we can sell it and see what it’s worth. Or the third thing is you can treat it as a real stewardship issue. It’s been handed to you. How can I make it of more value to pass it to the next generation? And that’s really what we try to do is try to say, this is an heirloom, it’s our legacy and we would really like to pass to the next generation. Yes, we could sell it, make a lot of money. But that’s not what life’s all about. Life’s about how do we treat our employees? How do we treat our animals? How do we treat our customers? How do we treat our community? How do we become salt and light in so many different areas? And so the business is really it’s not ours, it’s God’s. And how do we take care of it for him? Because some day we will give an account for what we did with what he gave us.

John Coleman: I want to touch on one thing you mentioned, because it’s another unique element to this business that doesn’t exist anywhere, which is the treatment of animals. Obviously, this can be a tricky sector and I’m sure that some family members are more sensitive to that than others, as are people in the community, in the pork business, obviously you’re dealing with live animals and there are slaughterhouses involved, etc.. How do you, as a business and a family, think about the proper care of animals in that perspective?

Phil Clemens: We actually go back to the Bible, talks a lot about it, and you take care of God’s creation in the best way possible. And we try to have the best animal welfare programs in the world providing space, providing proper diets, proper medical care for our animals. We try to really treat them really in the best way possible. And I will tell you this, when you treat the animals in the best way possible, they do actually produce a much better meat product. So it’s a full circle that comes around. But we look and say, I’m going to actually answer to God, how did I take care of his creation? Did we treat those animals with respect even though we’re going to harvest them and we harvest 22,000 hogs per day, so we harvest a lot of hogs and we take care of a lot of animals, but we want to take care of them in a proper way.

John Coleman: That’s remarkable, Phil. I want to circle to another concept I’ve heard you all talk about before, and maybe you can articulate it for us, which was this transition from a family business to a business family. And obviously this starts to lead into just the way in which you consult other families now. But what does that mean exactly? And what did that mean for your company as you went through that transition?

Phil Clemens: Well, let me just explain part of the process this way. When you look in the mirror each and every day, you know, you look and say, what do I see in the mirror? Well, it looks exactly like me, but it’s exactly the opposite. The same is true of a family business versus a business family. Now, let me describe a family business, and most of them are family businesses here, especially in the United States. Family members feel they’re entitled to a job. They’re guaranteed a job. Sometimes a parent say, we mandate you come to work in the business. And that’s what a family business. I have a job because I have the right last name and I become the employer of last resort. If I can’t get a job anywhere else, the family will hire me when I come to work at a family business. The rules are very different for family members than they are for any other employees. Whether it’s wages, benefits, anything, they’re just different for family. When it comes to leadership, the family always chooses the leader. Now, on some families, it goes to the point in time it’s got to be the oldest bloodline family member. Some it has to be only a male. But family businesses can also choose an outsider to lead their business. But the key is the family always chooses the leader. Finally, the main goal of family business is family harmony. We all need to get along. And I tell you this, when you have 380 family shareholders, that’s not going to happen. So family harmony is really hard to achieve. That’s why the average family business only last 25 years, only one third go to the second generation, only 12% go to the third generation, less than 4% go to the fourth generation. Wow. Now, when it comes to a business, family, family members are encouraged to come into the business, but they have to be qualified. They don’t get there because of the great last name or because they’re an owner. They get there because they’re qualified to come into the business. And when you come into the business, the only hat you can wear is employee hat. You can’t wear a family hat. You can’t wear a shareholder hat. Only a family hat. When it comes to leadership in the business family. It’s always to the most qualified. If that’s family, it’s great. If it’s not family, that’s okay. Also, because it’s the most qualified when it comes to work rules. Work rules are the same for everybody. You don’t get special privileges just because you’re a shareholder or family member, you know? And the business is there to help the family owners. In a family business, it’s kind of like the family comes in and it’s like the IRS knocking at your door. I’m from the IRS. I’m here to help. Well, in the family. I’m from the family. I’m here to help you run this business. That’s not a help at all. So the main goal of a business family is profitability. And as a result of being profitable, you can work on family harmony. Two models, exactly the opposite of each other. The unfortunate part about it, I would say 80 to 90% of family businesses in the United States operate under the family business model. They’re going down a pathway of unsustainability. But to make the change to a business family is extremely hard. It is not an easy process. And we went through it. I had to terminate some of our long term family member employees. I had to terminate our largest shareholder as we went through this process again, but still put on that hat. They’re still a family member. There’s still an owner. They’re just not in the business.

John Coleman: That’s got to be a remarkably hard process, as you described. And then to immediately switch hats from kind of owner or employee or CEO having to terminate these folks to a family member, comforting them and trying to rebuild relationships is not a seamless transition. You know, you’re consulting a ton of other family businesses now and you’re giving back partially by trying to help families be more thoughtful about the way in which they run their business. Where do you see that go wrong for families right now, or what are some examples that there are folks running, family businesses listening now we’re investing in them. What are some of the most common errors that you see?

Phil Clemens: Well, I think that one of the biggest errors is the title of entitlement. I’m entitled as the owner. I get to do what I want to do. I get the call, all the shots. It really is all about me, even though they don’t say it in that way. But that’s what really happens. And they go down a path. It’s a great destruction. Let me just go back to one thing that I try to share with the people I consult with is let me tell you economically what happened to us. And we did not do this for economics. We did it because it was the right thing for us to do. Our stock gets valued by an outside agency each and every year. In 2000, we went through this change. Our stock was valued at $30.62 a share. Our share price in 2022 is $2,065 a share. It’s been in a remarkable growth. We didn’t do it for the economics. But when you do things the right way, you do get rewarded.

John Coleman: That’s an awesome reminder. Phil, one of the things you’ve emphasized throughout, I think implicitly is this idea of being a servant leader and even listening to the way in which you approached your job as CEO and as chairman. Think about animal care, employees community. How do you personally keep a focus on a servant leadership mindset when you’re in that position, and particularly in a family business or in an owner operated business where, you know, there are all kinds of temptations with the economic benefits, with the way in which people treat you, it’s easy to lose sight of the fact that you’re actually serving others. How do you stay grounded in that context and continue to be a servant leader?

Phil Clemens: Well, let me start with the economics and then go back to the mindset. One of the things that we did in our company is we have a very strong profit sharing plan and bonus programs. Our bonus programs start with our hourly employees before any management can get a bonus. Hourly employees have to get their full bonus. And when it goes up the line that the supervisors or the other people get their bonuses, but the officers do not get any bonus until the people underneath them get a full bonus. And we’ve had years where the officers got zero bonus and everybody else in the company got full bonuses. Again, that’s putting yourself as the last one in the line rather than the first one. You know, the average business, the CEO, he’s the first one to get a bonus. And if there’s anything left over, then we’ll give it to others. We do just the opposite. And again, it’s because we have this servant leader mindset. One of the questions I like to ask people, how can I help you? Or How can I serve you? And it’s surprising when, as the CEO, when you come down and say, How can I serve you? They look and say, Oh, you’re the boss. I need to serve you. No, no. How can I help you? Because if I can help you, in reality, we help everyone. And how do we do that? And it’s a real mindset of when the person said we actually should change our name from the chief executive office to the lead servant. And to me, that’s what we want to be, is put others first. And when you put others first, it’s surprising how you get actually rewarded. But you don’t do it because you’re getting rewarded. It’s just the right thing to do.

John Coleman: Once again, what we see time and again is it creates an exceptional culture. And again, I firmly believe that culture is the greatest competitive advantage in business. It’s the hardest to replicate. You can’t flip a switch and create a culture and creating a business that people want to work in, where you’re getting the best talent, where they’re staying, where they’re dedicated to your mission, can create extraordinary performance and excellence in the business. But no one works for a leader who comes across as selfish or narcissistic and wants to be that dedicated to the culture. It just doesn’t happen. You almost have to have a leader who’s humble, who’s willing to elevate others, and who’s a servant leader to create the kind of culture that can outperform.

Phil Clemens: Absolutely. Let me just give you one story that just happened last year. Our current CEO told me he said we had an employee, a long time employee came up and said, I’d like to sit down and talk with you. I’m leaving the company. And the CEOs thought, okay, what did we do wrong? Why does he want to talk to me before? Why is he leaving? He came up and he said, Well, I need to move out of the area because I have some close family relatives that are sick. But he said, I want to come up and tell you how much this company has meant to me. Before we had one of our employee meetings, you ask everybody, is there anybody we can be praying for? And he said, I raised my hand. He said, My wife is very sick. And you said, Can we stop and pray for her right now? He said, You won’t know what that did for me. When the CEO takes time to pray for me and my family, he said, it’s the hardest decision I ever made to leave this company because this company means so much to me. But I’ve got to take care of my family.

John Coleman: Isn’t that extraordinary? I mean, that’s extraordinary. And you just love it because you feel as a leader. One of the things that’s closest to your heart, I think, or at least I know this on my end, is you want the people under your care to flourish. You want the people that you’re entrusted with leading to flourish, to enjoy their lives, to be fulfilled, to have a sense of purpose and meaning. And again, to hear that from someone. And to hear that that’s clicking and that they’re invested in it. It’s just one of the greatest rewards I think that you can have as a leader.

Phil Clemens: Absolutely is.

John Coleman: So, Phil, we’re going to do something fun now. We’re going to transition to the lightning round. We could go forever. And this is a super interesting conversation for The Lightning Round. We like to keep it punchy. We answer in kind of 60 to 90 seconds. Some of the questions will be a little bit fun. Some will be a little bit deeper. And then we always wrap up by asking people, what are you learning through God’s word right now that you’d want to share with others? And we prep people for that because some of us like me are bad at remembering verses. So give us a minute to collect your thoughts if you if you want to, about what you’re going through recently. But to kind of start the lightning round with a fun one, you work in the pork business or you’ve worked in the pork business. I imagine you, like me, are a fan of various pork products, whether it’s bacon or pork sausage or pork chops. Do you have a favorite pork product and how do you like to prepare it?

Phil Clemens: Bacon By far, bacon makes everything taste better. In fact, we gave our shareholders all a sweatshirt there that says Bacon makes everything taste better because it just it adds flavor to everything.

John Coleman: I’ll tell you, the first time I realized that was the first time I had chocolate with bacon in it. Bacon, chocolate. And I thought, oh, my gosh, there’s nothing that bacon doesn’t make better. Yeah, it’s true. On a more serious note, we’ve talked about a bunch of different lessons today. If there was one. One key message you could deliver to the CEO of a family business right now who is a family member, someone running a family business. What key piece of advice would you give them?

Phil Clemens: Develop a thick skin. People will say things to possibly hurt you. Just allow things to go right on through. Don’t dwell on them. Develop real thick skin.

John Coleman: As one of three brothers and a father of four, I just can’t imagine that siblings and family members would ever say anything hurtful to one another. Phil That never happens in our family. That’s.

Phil Clemens: It happens. It happens whether you’re a Christian family or not. That’s for sure.

John Coleman: It’s for sure. You know, this is such a unique area. One of the questions I have for you is, is there a good book or two that you would recommend to people thinking about family businesses?

Phil Clemens: Well, there’s a couple actually a book that’s not about family business, but I think it’s really good. Andy Stanley wrote a book called Principle of the Path, and the principle is direction, not intention determines destination. And so you really have to examine what direction am I going in, because every path leads to a destination and am I going to my desired destination or not?

John Coleman: Well, you didn’t know this Phil, but you won me over, Andy he’s my pastor. I go to Buckhead Church in Atlanta and I remember the original sermon with the Principle of the Path. And then I read the book and man, Andy just has such a magical talent for synthesizing complex topics, for making them simple and for making them. You hear it and you think, Oh my gosh, that’s obviously true, and it can help you reorient your life. And that’s such a talent, I think, for a leader which which I think Andy is, is to take the complex, make it simple, make it powerful, and make it such that it’s practical for people’s lives.

Phil Clemens: And his new book, Better Decisions, Fewer Regrets, you know, asking those five different questions, they can really help you in business to say, how am I really doing in business? From integrity to wisdom, just all the questions he asks are really, really important.

John Coleman: All right. One more fun question, one more serious question, and then we’ll turn to what you’re learning from scripture. You work in a pretty interesting family business. You’ve talked to a lot of family businesses. What is the most interesting family business that you’ve encountered?

Phil Clemens: I would say this every family business is unique, but each one is the same. And I would say that the family business said probably one that I worked with, which is really dysfunctional. They were in the cabinet making business and the father was one that. Just would not let go. And they just. If you talk about ways they could screw things up in different ways, they just couldn’t get out of the way of killing each other. It’s really a shame, but I think that’s probably one of the most unique businesses. How that people can treat family within a business is just unbelievable.

John Coleman: What’s the and we’ll do one last question. What is the best piece of advice you’ve ever received?

Phil Clemens: I think the best piece is engage brain before you put your tongue into action. You know, so often times we think we’re really smart. We can answer real quick. But if we stop and think first before we talk, it’s really, really important.

John Coleman: Here’s the danger. Phil, everybody listening to this is listening. In the past few years since I started hosting knows that I probably don’t do that often enough on this podcast. So that’s good advice for me to make sure I’m thinking things through before I spit something out, maybe to just close this out. Phil, I mean, you’re obviously such a thoughtful believer in your walk right now. What is God teaching you that you might want to share with others?

Phil Clemens: Well, I think God’s teaching right now is one of the greatest gifts he’s given us is choice. You know, the old saying is, you can choose your choices, but you can’t choose the consequences of your choices. Once you choose them, they make you. And if you go all the way back to Genesis chapter two in the Garden of Eden, he gave Adam and Eve a choice, and he said, There’s a consequence if you don’t make the right choice. And if you go to the Bible, there’s so many times that God has given us choices. You know, if you think of Jeremiah, he talks about, I have plans for you, I want a hope and to succeed. That’s a consequence of he says in the verses right after that, who you’re going to choose to follow. And that goes back to Joshua. Joshua, 24 Joshua asks the people, Whom will you serve the God of your fathers or the other gods around you? He says, For me, and my household, we choose to follow the Lord. And, you know, unfortunately the nation didn’t follow. But you look at Jesus, he says, Matthew 24, he says their choice Are you going to serve God? Are you going to serve money? You can only serve one. Which one are you going to choose? And there’s consequences for choosing either one. And I think to me, I’m constantly drawn to God. Why did you give me all these choices? Well, he wants us to be thinking. And how do we learn to make the right choice day in and day out?

John Coleman: Man. Phil, that’s such a good word and such a great way to conclude the podcast. It’s obvious talking to you why so many people respect you and seek you out for advice on these topics, and just a reflection of the great leadership that you’ve had through the years. So thank you so much for coming on today and sharing what you’ve learned with the listeners for the Faith Driven Investor podcast.

Phil Clemens: It’s my pleasure to do it.

Subscribe to the newsletter

Stay Connected
to the Movement

We know that as an Entrepreneur, your most valuable asset is time. So each month we take the very best of the podcast, the blog and all the news, resources, and upcoming events happening across the space and bring it to you.

Episode 139 – Marks on the Markets: Are We Witness a Great Tech Reset?

Episode 139 – Marks on the Markets: Are We Witness a Great Tech Reset?

Podcast episode

Episode 139 – Marks on the Markets: Are We Witness a Great Tech Reset?

Most tech headlines in recent months involve stories of layoffs and massive shifts. So what’s going on?

In this episode of Marks on the Markets, Jake Thomsen, and Ben Hames join host John Coleman to discuss the changes they see in the industry and what investors should consider as they start the new year.

The trio also debates about Elon Musk, the Metaverse, and whether or not Web 3.0 will live up to its hype. Someone even gets called a communist. 

It’s a jam-packed episode to kick off the new year. Make sure you follow the show on your favorite streaming service so you never miss another episode.

All opinions expressed on this podcast, including the team and guests, are solely their opinions. Host and guests may maintain positions in the companies and securities discussed. This podcast is for informational purposes only and should not be relied upon as specific investment advice for any individual or organization.

Episode Transcript

Transcription is done by an AI software. While technology is an incredible tool to automate this process, there will be misspellings and typos that might accompany it. Please keep that in mind as you work through it.

John Coleman: Welcome to the Faith Driven Investor podcast. This is your host, John Coleman, and we are bringing you our monthly marks on the markets. This is where we feature great Christian investors across the spectrum offering perspectives on current market environments. We are actually recording this right now just before the holidays, so there will be a longer delay than normal. We usually release this just a few days after recording, but we’ll be releasing this after the New Year. So happy New Year to everyone. We’re recording this just on the eve of Christmas right now. And we are hopeful that many of the themes that we talk about will be just as relevant a couple of weeks from now as they are now. I’d like to welcome today our two guests, Jake Thomsen, who leads venture capital investing for Sovereign’s Capital, and Ben Hames, who’s the CEO of Eight Ventures, Private Wealth in Atlanta.

Jake Thomsen: Excited to be here. A lot going on in the marketplace and in tech. So I’m honored to be with you both.

Ben Hames: Well, it’s wonderful to be here, John. Love the work you guys are doing through sovereigns. And I look forward to a good conversation today.

John Coleman: Well, today we have a very interesting topic in mind. We want to talk about the great tech reset and whether there is, in fact, some sort of reset going on within technology. Obviously, over the course of the last year, growth in technology stocks in particular will have declined. We’ve seen a slowdown in growth, equity and venture capital markets on the private side. And then there have been very high profile examples of disruptions within tech companies like Meta, like Twitter, which we’ll dig into a little bit more deeply coming up and across the board. So the first question I have for you all and I’ll start with Ben, maybe for the public markets perspective and just hear from Jake how that’s playing out in private markets. But is the current decline in technology stocks likely to go further?

Ben Hames: Yeah, great question. You know, I think we all understand the enhanced risk of what was effectively free money. It’s been a very cheap time to hold long term assets over the last two years. And with that, there’s a loss of discipline. And so if you look back, you know, a year or two years ago, you see some very lousy valuations, particularly tied to non-profitable tech. As you know, as I’ve been going through year end meetings and planning meetings for 2023 with clients, you know, we talked about what we did well, what we could have done better. You know, certainly look in the mirror as a manager and trying to look at those things and very much of a Warren Buffett annual letter style to look at pros and cons, what we did well, what could have done better. You know, one of the things that you really needed to do in 2022 is the rates reset and begin to normalize is to have avoided the big pitfalls. One of those was non-profitable tech, which has just been crushed. You know, our Cathie Wood followers out there have felt the [….] of it. You know, Ark innovation, ticker symbol ARKK down 80% alphabetized. And that’s really what it is. It’s a collection of interesting ideas, futuristic companies, disruptors, you know. But when you cut down to what the EPS, I think their 2022 number is, you know, almost $6 a share loss. Right. And this is trading at 160 plus. You know, now we’ve lost 80%, but still worth 30 something dollars a share and we’re losing $6 a share. Right. You know, you did the math on that. It’s just so dramatically different when you start to imply a real cost of capital. So, you know, again, you know, as I talk to folks, sometimes clients who are interested in those kind of investments, you know, over the last few years, it’s really been a, gosh, how do we even think about the value of these things? Right. This could be a great idea. This company could in fact, be a disruptor in the market. But we’re just out in space in terms of these valuations. You have a lot of companies who don’t even sniff a profit in the near term and they’re trying to tens of billions in valuation. So yeah, yeah. I think the big thing in 22 is I think about it is just really being exposed. If you were, you know, pretty heavily invested in non-profitable tech. So, you know, I’ll say one other thing and in wrap, yeah, as we think about, for example, the tech crash around 2000 and look at where we are today. I mean, you really do. You are anchored today by big, stable mega tech companies, companies that we live by. And really, those valuations are pretty interesting. Now, you know, I always go back to Warren Buffett like a good Christian, go into C.S. Lewis in investing, you know, we look into everything he has said in his annual letters and parsed those and learned from them. But, you know, if you like, if you like the stock, you know, this company at 40, you should love it at 30 and you should be banging in the desk to buy it at 20. And so, you know, I look at Google, I look at even Meta, which is, you know, interesting and risky. This stuff is beginning to look interesting. Make Tesla, you know, we’re now at 22 times next year’s earnings, I think. So again, those that love that much higher prices should really be interested now.

John Coleman: Yeah, you are right. That’s one of the things I see that’s different than the dot com bubble, which we can talk about a little bit. You know, we saw precipitous declines, but at that time, so much of it was really speculative technology, right? There wasn’t this floor of companies with genuine business models like Tesla is a good company. Amazon’s a good company. You know, Meta is a good company in its own right. At least you could argue it is improfitable, right. Some of these are profitable. And it does feel like a lot of the air has already been let out, although it certainly could face further declines Jake. How is that playing out in private markets right now?

Jake Thomsen: Yeah, so the private markets really follow public so much in the out of from what you guys are saying. I think that the SPAC segment about those tech companies is probably the closest to the dot.com. And I think we’ve seen a lot of that air let out, as you mentioned, John. And I think you’ve been you’re talking about Google and others. It feels to me that there’s an upward pressure on a lot of these companies that are inherently still very high quality. They’re cutting a lot of costs. Right. Google is expected next year probably to cut 10,000 people that an average salary of $300,000. That’s $3 billion. That’s going to go to the bottom line almost overnight. And so you think about that upward pressure or below that long term valuation multiples and yet interest rates are still climbing. Right. I think what we saw in the dot com bubble was as soon as everything popped, started getting a little bit higher quality in the fundamentals and then interest rates started going back down to call it six and a half percent, 1%. That’s where we really saw things starting to come back. So that’s what we’re watching for on the public side, because it does inform everything in the private markets in the later stages in private markets, ten, you’ll call it series B, C, D plus really mimics those public markets. What we’re seeing really interestingly on the earliest stages of seed especially is there’s still so much dry powder out there, so much that’s sitting in funds, still $200 billion or so that there are many fewer deals being done on the seed side. And yet the valuations are staying pretty steady. So it’ll be interesting to see from my vantage point are racing to come back and public markets recover before all that seed capital is deployed and those valuations start to normalize a little bit, too. But that’s the big unknown right now that we’re watching. But certainly seeing a lot of those valuations that have come down seem to be pretty steady below the long term averages. And that makes for a pretty compelling market to be investing in.

John Coleman: You know, you touch on one topic that I’m interested in, Jake, and I’d put this to either of you. I remember the very first time I visited Northern California to look at tech companies back in graduate school. I visited one of these companies we’ve named, which shall remain nameless, and it was just overwhelming the amenities when you walked in the door, right. There were, you know, recycled rainforest wood floors, and you were never more than a hundred feet from a full kitchen. And, you know, all this sorts of stuff that tech has become just notorious for profligate spending, incredible benefits, great if you’re working there. But the culture was one where money flow freely and there were a ton of fringe benefits. Now we’re really seeing the first round of layoffs with this new era of tech, even at the big and profitable companies like Meta. Is that going to change culture? You know, do you think these layoffs are going to be consistent throughout the industry? Do you think cost saving now becomes something that tech companies look to to generate profitability? To your point Ben and what does that do to the culture of Silicon Valley and the culture of technology?

Ben Hames: Yeah, I mean, I think it’s really part of this reset where you do have a real cost of capital now and you have a new focus on the bottom line and earnings per share. You know, not to suggest that 2021 for Meta is, you know, should be the baseline of what we would consider normalized earnings. But, you know, at the moment, it varies in a moment, day to day. But, you know, we’re trading at about eight times 2021 earnings for Meta. We start thinking about companies that get in the mode of manufacturing earnings, what you can do with the levers of expenses and hiring and whatnot. I mean, this is about many measures, a very cheap company if they want to continue to do what they’ve done. And it does a little bit more about Meta, though, in which I think it’s such an interesting investment case right now. Yeah, they have that problem of this is, you know, a industrialist who’s been very successful at everything they’ve done and now they want your money to go and, you know, have a number of venues drive it. So they’re kind of transforming themselves as they transform into the the metaverse dominant player into something different. Right. So there’s a lot of concern that goes with that. And expenses have been through the roof in that transition. So again, that that’s part of the thing that makes this is such a difficult case to analyze in terms of future investment. But again, I think you’re seeing those companies, you know, Google, Meta begin to cut costs, to focus on that. And I think that bodes well for tech investors.

Jake Thomsen: Yeah, I jump on that and say it seems like a lot of these companies are going to follow the playbook that you see Microsoft and others playing where you get to a certain level of maturity and you can start to wring out some of the costs. And Wall Street really respond to that. And this is a time in the cycle where some of these companies are looking for that impact for shareholders. So I do think we’re headed that way. Even the dynamics, the fundamentals are back ten, 15 years ago when you had 10% of graduates in Silicon Valley were computer science majors. Right. These days, it’s more like 50 to 60%. You’re starting to see that supply, which sure, there’s a bit of a long tail to get in the system. But once they’re in there, there’s just a lot less competition for them. So I think you’re going to see more of these maybe almost in a ratchet effect where bringing it down is part of the cycle. I don’t know if they’re necessarily you’re going to come back, but I do think it’ll impact culture because a lot of folks didn’t sign up to be at these kinds of almost feels like PE style bring out the costs. Right. To figure out how to increase the bottom line. A lot of these tech folks, they signed on a very different company. So be interested to see how that change in culture impacts retention. A lot of developers of top tech companies.

John Coleman: Well, and I want to zero in on the people side of this, Jake, because you and I have talked about it before. I’m just consistently struck when I look at technology companies, particularly bigger ones, how few people within the companies are actually engineers. So, you know, there are a number of different positions. I can’t for the life of me understand a lot of titles within the companies and just understand what people do. And I think this idea that tech might be radically overstaffed, so not by ten, 20% overstaffed, but potentially 50, 60, 75% overstaffed, really came to a head with the Twitter acquisition by Elon Musk. Right. I mean, in the first three weeks, he took that organization from 7500 people to 2700 people right in the course of three weeks. So we’re not arguing necessarily that that was done well or that that’s the right way to do things. But I know a lot of folks in Silicon Valley have been watching to say like, oh, my gosh, are we really operating at more than twice the number of people we need to do well and have we so overstaffed on non engineering or non-technical people that we’re actually diluting the impact that those folks can have? What do you think about that? Because I actually believe it could be true in a lot of tech companies that they could be twice overstaffed what they need to be to be effective. But maybe, Jake, starting with you and then to you, Ben. And what do you see? Do you think that might be the right case or do you think that that’s swung too far, that what happened at Twitter was ineffective, there couldn’t be as effective in other places?

Jake Thomsen: That message resonates for me, for public companies and later stage companies and analysts acknowledge, too. Of course, we’re talking about big numbers of job losses in the rest, and it’s really easy to talk about them as numbers. Right. So just wanted knowledge and honor that these are individuals and families and that’s hard. So I’ll start with that. But what we’ve seen is a lot of these tech companies, you grow to a certain size if you’re a public tech company. And there’s a sense where complacency is forgiven, right? Where there’s not the same scrappiness. Right. Elon got it. This was like, hey, we’re going to work long hours and we might even work on weekends, right? Which had a lot of people up in arms because getting back to the roots of really hard work and this is completely anecdotal and unfair because I know it’s incredible individuals at all of these companies, but I think about the developers at top tech companies, public companies that I know they’re probably putting in 30, 35 hours a week. Right. That in some cases includes video game time, right. At these really, really fun jobs. And the developers I know and all the startups will be back are putting in at least double. Right. This is a totally different culture. So I think there is some element of that culture in that what some might call bloat that you simply can get rid of and a company is going to be okay. But there’s also very rational side of that that I’d say where tech companies tend to be these lean startup mentalities, right? Build, measure, learn. You don’t always know what the market wants to go build something, see how reacts. Where do we reinvest then? And when capital is cheap or free, it makes a lot of sense to overstaffed, to go seed something, to see where it goes. But once capital starts to increase in its cost, then I’ll set the ROI of those kinds of endeavors, whether they’re moonshots or everyday efficiencies that starts to go down. So I think there’s a very rational case to be made where when capital’s cheap, you kind of want to air…. The bloat in tech and then now there’s coming back down from more expensive. You’re going to see a lot of those that they just no longer make sense. Status positions.

Ben Hames: Yeah you guys are great in sight Jake you have a lot more experience on the ground with those companies and operators. But I will say, you know, I reflect on what had been some bizarre business news stories of the last couple of years related to this, you know, one being the collusion among tech companies to not poach from one another, which is such an, you know, an odd time, you know, but then also the later variety of that story has been the hoarding talent, you know, that you would have these counter-accusations between these big hard entities where they’re, you know, you don’t need these people. You’re hiring all these extra folks and taking them from the market and harming the market in general. You know, again, a very strange time. You know, I will say a lot of the broader discussion in the economy right now and certainly with markets where we have a severe recession going into 2023. You know, I think a big part of that is hiring. We’re talking a little bit about layoffs in the tech space, and we’re just focused on tech in general today. But more broadly speaking, you know, hiring is still happening at a pretty robust clip. I think in 2019, the average monthly new hires was 164,000. Latest numbers from November. 264,000. So the hiring is still rapid in the face of this bad hype campaign. So, you know, again, we’re getting some headlines and some of the tech layoffs and these big companies and again, some new fiscal discipline that I think most tech investors will welcome. But as of right now, I think there’s 4 million more job openings that are unemployed Americans. And this is a big part of the recession discussion, the inflation discussion, but still persistent inflationary pressure on the wage fraud. As you look beyond tech and across the economy, significant tightness in the labor market.

John Coleman: Well, and that’s why it is so interesting right now. Right. Because typically when you raise rates like this, it does cause a recession. There’s a chance we’re in a recession now. There’s a chance that we’ll see that deep end next year. But thus far, it really hasn’t played out in employment. Right. The labor markets are still relatively tight. Consumer spending seems to be relatively strong right now. There are certain segments that are very interest rate dependent that have obviously got hit very hard. You know, new home building or mortgages, etc., are in a difficult spot right now because of rates. But there hasn’t been the kind of real economy hit that I think you would expect after such dramatic rate tightening yet. And the question is, of course, whether that does hit. I don’t want to spend too much time on this necessarily, but it’s hard to talk about technology right now without talking about the private company, Twitter, and obviously the activities of Elon Musk as of this recording. Musk has done a survey on Twitter about whether he should be CEO and has decided to step down. There are a whole host of implications because Musk is really at the top of a number of the most innovative companies in the world. Right. SpaceX, Tesla, Neuralink, and now Twitter are all in very different areas. And he seems to have his hands on a lot of those spaces. Right now, Tesla stock is cratering as a result partially of people believing that he’s distracted. Twitter obviously took on a lot of debt, maybe just starting out of the gates. I mean, Jake, what’s your impression of what’s going on out there? And is Elon still, you know, a genius? He’s going to be able to turn all this stuff around or has he finally met his match in what he’s taken on here? What’s your read on what everyone’s talking about right now in Silicon Valley?

Jake Thomsen: Yeah, the only thing I can say with confidence is I’ve considered canceling my Netflix subscription and just read Elon’s tweets over the last few weeks because they are oh, my gosh, they are golden at times. And it is it’s you know, you would not expect a public company CEO to be engaging in some of those ways, but it’s anybody’s guess. You know, some folks will say, why is he wasting all this time here where he has all these world changing companies that he should be leading and really focusing on? And I think there’s a case to be made that Twitter is our de facto public square. It’s worth the focus of somebody really, really smart. And I do think that he’s working really hard to extricate himself from Twitter. He’s trying to hand over some folks that, at least from what some people are saying, weren’t that interested in taking it on Twitter. He doesn’t have the heir apparent at this point. But I would say, you know, it turns out empirically there are really only three categories or three times where a public company CEO deeply drives an outcome in terms of value creation. The first one is when they are the ones that are setting culture. Right. And there’s more research on this happening in the faith driven sphere, especially. The second one is when there’s a major transition. The third one is when the company is a very innovative company and the CEO is driving that innovation, all of Steve Jobs. And so it’s such a good question. Longway we’re just getting my affirmation of your question because he’s such a smart, gifted guy who probably does drive to [….] that a lot of these companies are delivering, especially the earlier ones like the Neuralink’s and others that are potential categories in the future that need him in the earlier days more than maybe Tesla does or others that have a bevy of engineers and leaders. But it’s certainly a notable time watching a leader like Elon.

John Coleman: Yeah. What do you think, Ben? I mean, you’re watching this, you have talked about Tesla before

Ben Hames: I’ll try not to get too lost in the weeds of that momentary headline, such Elon is really good creating. You know, I hope in the rearview mirror a year, ten years from now, Elon Musk will be a champion for free speech. And I think he is positioned to do that. Maybe he does that more effectively as the owner and not the guy who’s, you know, fighting with tweets. It’s hard to do, right? It’s hard to do well over an extended period of time. You know, if I am a significant Tesla investor, I probably would love the idea of him not continuing to operate as he has in these first few days and weeks. So, yeah, remains to be seen.

John Coleman: Well, you know, he’s got good teams there. I think everybody knows that. SpaceX, Tesla and Neuralink are now, or at least SpaceX and Tesla seem really deep. I’m less knowledgeable about Neuralink, like you said, Jake. Part of me thinks, gosh, you’re getting to Mars, creating full autonomy, creating human computer interfaces like why?

Jake Thomsen: And doing the blue chips. One of these things does not belong. Yeah, exactly.

John Coleman: But you’re right. I mean, this is look, if you think about the culture, this idea of a public space, of speech, of what’s acceptable, of how we should communicate with each other is a cultural touchstone right now. And and certainly his instincts have been very strong historically about what was needed in the moment. And those companies seem to be creating durable values. And you look at SpaceX. Not only are they going to Mars, but they have the broadest satellite network in the world now. I mean, they’re delivering Internet to Ukraine right now and to hurricane stricken areas. It’s just fascinating to see what that will look like in the future. Moving to another pretty notable entrepreneur right now, Mark Zuckerberg. You know, Mark made this massive bet in transitioning Facebook to meta, moving away from social network to creating the metaverse. And I think he’s bet billions of dollars or tens of billions of dollars on creating the metaverse. And so far, Meta has really gotten punished in the public markets partially as a result of the downturn, but partially because a lot of the hoped for success in the metaverse, at least within the context of that company, has not materialized. Jake, I know you’ve invested in the space. Is the metaverse dead or are we going to see some sort of resurrection here? And is Zuckerberg on the right track, or do you think there’s actually needed a pivot right now on how we think about it?

Jake Thomsen: I don’t think Metaverse is dead. I would probably, as a meta observation, so to speak, I’d say this is a reasonable bet from his perspective, because you see, the long arc of innovation is that some of these these hardware’s over the last 30 plus years have gone from desktop to laptop to mobile. And a lot would say that augmented reality, virtual reality may be the next on that path. Right. And they’re increasingly ubiquitous, they’re increasingly immersive, they’re increasingly part of our lives. And so it’s not crazy to think, especially when glasses come out right, where you’re almost RoboCop style. You bring the glasses, you can see through them. But maybe the three of us can be sitting in a room engaging with each other. Right. For instance. And people oftentimes think of virtual reality, just little clunkier, fewer use cases. But as Oculus comes out with its pro headset, which is already announced as Apple comes out with the headset next year, I think we’re going to see continued interest in this. I don’t know if it’s truly going to be the integral part of our lives that Zuckerberg hopes, but I think it’s a reasonable bet because what he’s doing is he’s standing against the innovator’s dilemma, right? Where you get to be such a big company and something is working and that thing that is working, all the stakeholders have an incentive to just keep focusing on that and then eventually somebody leapfrogs you because you’re not thinking ahead. But he’s investing downstream of consumer behavior, and that’s a really important thing that startups can do. But oftentimes public companies can’t necessarily. But because of the voting structure, which is frustrated, some folks is able to. So I think the metaverse holds a lot of promise. It probably doesn’t look a lot like what most folks think it would. And from Meta’s perspective, I think it’s a reasonable bet, at least in the medium term.

John Coleman: What do you think, Ben? What’s your metaverse avatar right now?

Ben Hames: Yeah, that’s what I wanted to get into. I was hoping we would go there. Yeah, I have mixed comments here. You know, first and foremost, you know, more of us living more in an alternate universe and taking advantage of kind of products that will be offered in the metaverse strikes me as a dystopian situation. But from an investment perspective, you know, there has been this trend, as Jake outlines of, you know, further and further entrenchment into our lives and more time spent aiming and interacting virtually. I mean, my goodness, just think of Zoom and and its competitors and how that’s reshaped work life. Yeah, it’s going to be interesting to see. You know, again, I think if I could just talk a little bit about the investment case for Meta. You know, there’s part of me that has to keep in mind the ability that they would have to just retrench and go back to the tried and true model that they have and pull those levers. And all of a sudden you have something that’s really valuable, not that risky, and trading at a pretty cheap price. And so, you know, again, I sort of view it as a this may be a disaster for Meta in terms of the foray into the metaverse and the big expenses, but it may in the NBA blip and they go back to the old Facebook and advertising and making a whole lot of money.

John Coleman: Yeah. And you know, the other Elon twist here that’s interesting from my perspective is, you know, it’s been a taboo topic forever to have social media companies charge their users. Right. It’s been an advertising model. The user has been the product, they sell data, etc.. And Elon has kind of opened Pandora’s box, so to speak, on trying to charge people for the blue checks, which Jake noted $8 or $11 if you’re on the Apple store. And one thing I’m interested in watching is if that does get some traction, which seems moderate so far, whether that impacts the core business models of some of the other social companies and whether they try and adopt that much the way that media companies have, you know, media companies, for a long time, it was thought that online information was going to be free. And now paywalls have gone up around the number of media companies and even substack, which is something in between social media and a media company obviously charges for newsletters or has authors charge for newsletters. So I’m fascinated to see where that ends up as well and what the charge model will look like moving forward. To speak of a more precipitous and obvious decline before moving into something really interesting and hopeful that’s happened as of this recording very recent news, Sam Bankman-Fried is on his way back to the United States, where he faces potential jail time or I think he may have already been transferred to the pen in New York. News today was that his two counterparts, Caroline Ellison and one of his co-founders, have turned on him and so have pled guilty to their charges and are theoretically cooperating with authorities and FTX obviously just suffered a precipitous collapse. Kind of same question with the metaverse, with the collapse of FTX, with the collapse of so many coins around this web 3.0 was supposed to be the next big thing between bored apes and cryptocurrencies in these exchanges is that dead is web 3.0. Do we need to find a web 4.0 now? What’s next Jake?

Jake Thomsen: Yeah, I say it’s not dead but is indeed hung over. So it feels dead, but it’s going to pull itself out of bed.

John Coleman: It’s mostly dead, as they say in The Princess Bride or.

Jake Thomsen: Yeah, that’s true. They are doing this, but it’s getting nursed itself back to health. And I delineate two different parts of this, right? One is the core web. Three, the blockchain technology part aside from crypto. And to me that feels like such a logical progression to say it is inevitable. Is it based on word? But did you use a taxonomy like web one was? We read the internet, right web two is we read and write right blogs and Facebook and the rest. Web three is really about reading, writing and owning. We own our information, we own our content, we own our contributions. We benefit from contributions to social networks. Right. And that that is something consumers are going to want. It’s going to be consumer demand. So those companies that are building on a web3 blockchain technology are going to be the ones that do very well in the future. So I don’t think it’s as a category. It’s dead. What I do think is we’re not going to talk about it quite as much in the same way we don’t talk about Internet companies, we don’t talk about AI companies, we talk about tech companies because those things have become such an integral part of those technology stacks. They’re just part of companies. Now, I think we’re going to see the most innovative tech companies built on web3 infrastructure. They won’t be a Web three company, they’ll just be a tech company. So I think that’ll stick around. It’ll be maybe a little more muted longer term in terms of crypto, which is the juicy part of the sector. I’ll tell you that the analogy that resonates for me is it is a force that was in need of a fire for its own long term health. It’s really hard in the meantime, but you got to you got to have that pruning of the ecosystem so it can really grow. And as we talked about before, they’re just thousands of thousand points that probably shouldn’t exist. I think a lot of those go away. Even the really good coins that weren’t the main ones, but some of that, old coins in that were really good business cases. I think they had a problem of governance, right, where you would have some of these founders that made their money before they really created values, they cashed out and weren’t aligned long term because they were in the tokens rather than the equity. What I do think is FTX this whole debacle is going to put a focus on governance. Then investors will say, All right, I like this project, but we’re going to make sure we align these interests. And that’s going to enable these incredible founders with good technologies, good products to actually come out of the rubble. I think there will be a handful of some the best web3 crypto companies that will come out this time. But it’s not a space that I would necessarily recommend anybody go and start pouring lots of money into right at this point.

John Coleman: When I like your description, Web 3.0 is about what we own and part of the FTX debacle, right, was people thought they owned something that was actually being traded and owned by Alameda Research. Right. Which was FTX was practically personal family office. And that was all of this is allegedly, of course. But, you know, that was a real betrayal of the underlying infrastructure of that and people becoming nervous about what they actually own.

Jake Thomsen: Well, I’ll add to that that the Web3 enthusiasts would say, well, the big problem is that was a centralized exchange. So the problem, web3, is that could have been defi decentralized finance, where you didn’t have somebody like SBF that’s calling all the shots and you would be unable to do that because the math would be unable to do that. Right. An algorithm can go buy a penthouse in the Bahamas, right? Only a person can. And so a lot of folks would say if that were truly set up on web3 infrastructure to then trade web3 assets, then you wouldn’t have had the FTX debacle.

Ben Hames: You know, it’s interesting you bring that up because I hear a lot of versions of that with regard to crypto and what’s happened in the last year, which, you know, again, maybe there’s some merit there, but it strikes me as very similar to the arguments we always hear about communism. It’s never been practiced. Is it true to its form? Is there have been done well and if it were, it would create a utopia. But you know, you think about all the things that and I’m you know, I’m out there and have been for a long time. I’m not a fan of crypto, you know, all the things that it was supposed to solve, you know, it really has failed with flying colors quickly. Yeah. Yeah. You see, you know, there’s an effort to differentiate, right? Is it Bitcoin is the thing. You know, I’m in that crowd. I can’t get past. I don’t know why it’s worth anything. Right? I mean, was it overvalued at 60,000? It now is worth 16. You know, again, we kind of go back to some of those valuation discussions we had earlier thinking about valuing companies by that op ratio or you know, we haven’t talked about some of the alternative valuation methods, but, you know, the rule of 40 or some of the things that people would use in the tech space, you know, where we have some tools where we can try to assess and apply value. You know, to me, the fact that blockchain technology is a valuable technology and will continue to be more valuable in the future, it just implies no particular value to crypto, right? I mean, it’s a non sequitur that bitcoin is worth $500, much less 17,000 because blockchain technology is valuable. Yeah, that’s the case I would make is though, you know, I just can’t get comfortable with this at any price.

John Coleman: Well, and Jake, since Ben did just call you a communist, I think you get to respond.

Ben Hames: Well.

Jake Thomsen: And is a good thoughts, comrade. But I mean, you know, those are all great thoughts and and the right kind of question that we need to be hold in the industry, too, over time. I suspect I see all the innovation come out of bull markets there, and I do think there’s more value it created over time. It’s got to have an actual problem being solved, whereas much of it doesn’t yet. So a little bit to be determined and it’s a fair, [….]. Absolutely.

John Coleman: So I want to kind of close we’re going to close formally on asking what you guys are learning through scripture right now that you want to share with others. But as we pivot, you know, we’re thinking about a great tech reset, right? There’s been a collapse in these markets. They’re undergoing layoffs like the dot com bubble. What came out of that was much different than what went in. Right. We came out with a more stable base of real companies that were growing after that. As you guys look at what’s happening today and we reset valuations in technology and also potentially where people are focused, what are you most excited about in technology right now? So maybe, Ben, start with you, but are there areas of technology that you’re excited about investing right now?

Ben Hames: Yeah, it’s I think it’s really hard to pick the winners in this space. And so partially, I’ve sort of hedged the bad in this space by making some broader plays. But I really like cyber. I think that’s a part of the spin that is going to grow. You know, I think, you know, we’ve recently seen in business news there’s a large zeal for all going on and the banks are are working together to determine how to refund those defrauded and that sort of thing. But again, it’s hitting us on all fronts. That’s the space that I want to be in and want to be exposed to have been and continue to think that’s an important place for folks to have exposure.

John Coleman: Jake, what do you think? Where are you guys focused as you look at early stage tech companies right now?

Jake Thomsen: Yeah, I’ll offer a bit more. General answer and more stage focus. And that’s really in the series A. As I mentioned, that’s not an area that I’d start to see the valuations coming down. A lot of companies that raise, call it 12 to 18 months of capital in the last year. So they’re coming up maybe mid 2023 to raise capital. Do you find a company that is capital efficient actually solving a big problem with a greedy creative leader? There are a lot of companies that unfortunately are holding period of time I think PE is going to take out a lot of the other ones that are at really good valuations. So I think the playing field is going to be winnowed a bit and these are going to be types of companies that longer term are going to be successful. And I think the valuations make that even more than seed and more than later stage. Really compelling, particularly because seed and series A they tend to be the highest performing in terms of internal rate of return for a very early stage. So that’s what we’re really looking at over the next six, nine months in particular.

John Coleman: That’s great. And I would just add two thoughts from my end. One thing that’s really caught my attention lately is artificial intelligence with chat GPT coming out and proving some of the power of that technology and that we actually have crossed the threshold at which that technology has consumer applications and is good. Right. You use chat GPT. And for its current use case, it’s actually a remarkable piece of programing, a remarkable piece of technology that’s likely to unlock a number of other things, both good and bad. But AI is on my radar, and I still think we’re going to see a lot of innovation in health care right now, particularly remote delivery of health care, telehealth, virtual health care. You know, that was a hot item during the pandemic because people couldn’t get physically to their health care. But it just seems like a lot of the stickiness of that model is starting to manifest in the market. And I just I think there’s a lot of innovation to continue to happen in this space of more bespoke health care delivery, particularly things like telehealth, which is one thing I think will make people’s lives better, but also could present some interesting investments. You know, we always like to close this because it’s the Faith Driven Investor podcast, and I know you two are both great men of faith with you offering just your thoughts on what God’s teaching you through Scripture right now that you might want to share with others. And so if you don’t mind, Jake, we might start with you and then Ben, you can close us out.

Jake Thomsen: I’d be happy to set the bar very low. So we’re going through a study. This is actually at work with our investment team, going through a study now. And what we highlight recently, Joy and I was just very struck reading of scripture about joy of how elusive, sometimes true deep joy can be. And there’s a quick framework of this that joy involves. Step one just recognize the way that Christ is in the day to day, right, of all the various blessing that we have. Number two, trust him in those moments where it’s not necessarily easy to see how things work out. And number three, thank him. Right. Almost a discipline of Thanksgiving and how if we can do those things consistently, it cultivates joy in our hearts. And this has been a big blessing to dive that top and joy in the season. Even with everything go on the markets where it’s easy for our heads to be steady and the rest, and yet our hearts do still go up and down with market.

John Coleman: It’s a good word, Jake. Pastor Ben, what do you think?

Ben Hames: Well, that I’ll it’ll be tough to follow that. You know, I will reflect on something that Erin and I had recently. I of course, Erin’s my wife. We were recently reflecting on. We have for 20 plus years now practice the Sabbath. I guess it’s been about 20 years to study. While we were in seminary, we determined that we should continue to honor and practice the Sabbath in a way that is sort of countercultural, even within Christian circles. And yet we were, as we reflected on 20 years of doing that. You know, I can recall that early along at certain points, you know, I guess on occasions feel somewhat restricted, the things that we said that we wouldn’t do on Sunday, you know, as we look back through the seasons of our life now 20 years of marriage and now I have a ten year old and a six year old. This has was such a gift, right, to have this sacred day that will you know, we won’t lead our ox into the ditch. We’ll do the work. We do all the things we need to do to have that day set aside and to disallow ourselves or to imagine that God intends for us not to work and have others work in our stead on that day. You know, in a busy world, in a stressful two or three years here with COVID in these things, that has been such an incredible gift for us and just, I think, imparted such peace, such time for worship, for family time when we just said this is what we can do. I mean, I’m reminded of an old Hebrew parable where, you know, there is a gentleman who is walking in his field on a Saturday and he sees a fence that needs repair. And he has this idea that he won’t even be able to repair it because he saw it on the Sabbath. Right. But, you know, just that that kind of idea that we’ve tried to live out and then no doubt very roughly and poorly by some measures, certainly of some of our Jewish friends that do so well. But I would just commend, you know, some type of Sabbath to all my friends and those I would care about. It’s something that’s just been very life given. For us as a family.

John Coleman: Amen and Amen. Well, Jake Thompson, Ben Hames, we are really grateful for you spending time with us today on the Faith Driven Investor podcast. I know I feel like I’m leaving with a better perspective on technology in the marketplace and certainly the wisdom that you shared on your own faith journeys has been important. So thank you all for joining us today and we hope to see you again soon.

Jake Thomsen: Thank you, John. Thanks, Ben. Good to be with both.

Subscribe to the newsletter

Stay Connected
to the Movement

We know that as an Entrepreneur, your most valuable asset is time. So each month we take the very best of the podcast, the blog and all the news, resources, and upcoming events happening across the space and bring it to you.

Episode 139 – Marks on the Markets: Are We Witness a Great Tech Reset?

Episode 143 – Marks on the Markets: Predictions for 2023

Podcast episode

Episode 143 – Marks on the Markets: Predictions for 2023

Each month, we bring in experts to give an overview of the market’s current state.  On this episode, we have frequent contributors Bob Doll and David Spika take us through their 2022 reflections and predictions for 2023. Bob is the Chief Investment Officer at Crossmark Global and David has the same role at GuideStone Investments. Both men bring incredible insight to the conversation.

Throughout the conversation, the two also chat about how Christian investors can think through layoffs, the potential recession, and ESG investing. David even makes a Super Bowl prediction.  Check out the episode and don’t forget to rate and follow the show on whatever platform you use to listen.

All opinions expressed on this podcast, including the team and guests, are solely their opinions. Host and guests may maintain positions in the companies and securities discussed. This podcast is for informational purposes only and should not be relied upon as specific investment advice for any individual or organization.

Episode Transcript

Transcription is done by an AI software. While technology is an incredible tool to automate this process, there will be misspellings and typos that might accompany it. Please keep that in mind as you work through it.

John Coleman: Welcome back to the Faith Driven Investor podcast. This is John Coleman and this is our monthly Mark’s On the Market podcast, where we talk to experts in the industry who are also people of great faith about what they’re seeing in markets and highlight some of the best Christian minds in faith driven investing. Today is a real treat because we certainly have some of the greatest Christian minds in Faith Driven Investing in Bob Dole and David Spika. Bob is the Chief investment officer of Cross Mark Global Investments. David is the President and Chief Investment Officer of Guide Stone Capital Management. Both have extraordinary careers in the industry. They have a record of success and we are so grateful to have them on today. So welcome, Bob and David.

Bob Dole: Thank you John.

David Spika: Thank you. Happy to be here.

John Coleman: Well, we want to dive right in. You know, we’re entering the month of February here. Before we look at this month and 2023, talk to us about your big takeaways from the market in 2022. And Bob, maybe you could kick us off.

Bob Dole: Sure first word that comes to mind is, wow, I mean, what a year it was in so many ways, mostly on the negative side. You know, when you do these ten silly predictions every year and we actually did say stocks and bonds would both be down in 2022, but never thought it would be by the magnitude. It’s the first time in 50 years that stocks and bonds were both down three quarters in a row.

John Coleman: Wow.

Bob Dole: I think that’s a superlative. I’m also struck by the amount by which value outperformed growth and the environment that transpired. You would expect that, but the magnitude was amazing. The final thing I would say off top of my head is how well international stocks did versus U.S. stocks. All those problems internationally and of course, international markets, most of them went down, but they went down less than the US.

David Spika: Yeah, I don’t want to trump you, Bob, but I had seen that we saw stocks and bonds both down more than 10% for the first time since the seventies in the 1870s.

John Coleman: Whoa.

David Spika: Yes, indeed. I don’t know what bonds we were trading in the 1870s, but something was being traded. So it’s been a long, long time. The thing that struck me about last year, though, was how ill prepared we all were for what occurred. If you go back and look at what the market expected for Fed rate hikes in December of 2021, I think we thought the Fed was going to raise 25 basis points two or three times. We ended up going up 450 basis points. Nobody is prepared for that. Nobody was prepared for 9% inflation and that caught everyone off guard. And I think what it taught us is that we can’t get too confident in our expectations and our predictions. We have to be willing to pivot and to humble ourselves and say, I was wrong because things often turn out differently than we expect.

Bob Dole: Well-said.

John Coleman: Well, and speaking of pivoting, we have flipped the calendar year, Bob. It was a crazy year in markets in 2022. It’s shaping up to be an interesting year in markets this year and in the business community. One of the trends that we’re seeing really prominently right now is layoffs among technology companies, including many companies that have never broached this before. Firms like Amazon, Google and Meta have had large layoffs, succeeding all those announced at Twitter previously in the Go Private there. And a host of other tech firms have made similar moves. David, I want to start with you. What does this tell you about tech companies in the U.S. And do you see these layoff announcements, apart from the human implications which will come to you as a positive or negative for the future of those companies?

David Spika: I think what we need to recognize is that what’s happening in the economy, whether it be in tech companies or financial service companies, is we’re seeing the job market start to weaken. Now, there’s two things that have created the situation we had over hiring during the pandemic, particularly the financial services sector. And we’re also going into a weaker economic environment. Labor has got to weaken and that’s what has to happen. The Fed can’t engineer a better supply chain, but they can engineer weaker spending. And that’s exactly what we’re seeing with these layoffs.

John Coleman: Bob, do you have any thoughts on the layoffs that are happening?

Bob Dole: You know, first of all, I agree with David. What I add to it is, look, these companies are facing top line growth is slowing and inevitably they’re concerned about profits and profit margins. And where is the economy going? How long will this weakness last? And so they have to trim their costs. And for a lot of tech companies, the biggest costs, labor. And so we’re seeing these announcements probably more to come. I guess what I would add is tech companies don’t have a lot of people compared to a lot of other industries. So the reason the job market, so far has remained strong as the big employers, retail, restaurants, they’re still looking for employees. They can’t find them at the wage rates. And so we see these tech layoffs and they are big and they’re important. But relative, the size of the labor force still not affected things all that much.

John Coleman: Yeah, we’ve been talking in our firm a little bit about the movement in technology potentially being structural in that they had become extremely overstaffed, potentially. I think Twitter was the canary in the coal mine there. There were a lot of folks who weren’t performing functions that were critical to the operations of the business. And a reckoning was going to happen at some point. And David, you know, to your point about this being really a cut primarily of the over hiring from the pandemic, I think a lot of these layoffs that have been announced, even though they’re quite broad, are actually just returning to something like 2021 or 2020 staffing levels. You know, this hasn’t cut deeply. And from my point of view, it is, again, will come to the human implications. But just from a leadership of the company point of view, it’s encouraging them to see them emphasizing discipline as part of their management toolkit. Now, where they haven’t had to do that quite as much in the past.

David Spika: And John, on that point I saw recently where BlackRock, even though they’re laying people off, has stated that they want to keep employment levels flat this year. So they may be replacing higher wage workers with lower wage workers as a way to manage their costs. Bob’s right, 70% of their costs are labor, so that may be part of what’s going on as well.

John Coleman: Let me zero in on one topic here and maybe, Bob, you could lead us off. When we talk about layoffs. Obviously, there’s a financial component to that within companies, but there’s a human component. We may be heading into something like a recession. It may not be as deep as some people think, but it may. As Christian investors and business leaders. How do we think about layoffs and how do we think about treatment of employees in times like a recession when these reductions become necessary?

Bob Dole: Yeah, great question. I think we start with the observation that, look, business cycles are part of life and you get expansionary phases where you hire, hopefully not over hire or perhaps they do this, we just comment it and then you get the other side of it and you’ve got to trim your costs. And labor is one place that it goes. I love employers that have variable part of the compensation, so they may end up laying off fewer workers and spreading the difficult news across the workforce more so we pay attention. That sort of thing, of course, is how do you handle as a company the policy of a layoffs, You know, how do you treat your workers? Is there a period of time where you hold them over? Is there a method by which under certain circumstances you can come back? What is the safety net that might be put in place? Are we treating this people as human beings rather than just numbers? And that’s, in my view, part of the values based investing. How do companies approach the layoffs that can often be necessary?

David Spika: Now, something else to note is that we have a responsibility to God and to our clients to deliver the best products and services we can. So if you go back to the old Jack Welch model, what did he do every year he got rid of the D players. Now, that sounds very callous, but in an environment like this where the job market is so strong, this is an opportunity to help some of the folks that really aren’t a good fit in your firm, find a better opportunity someplace else. And the good news for them is there’s 4 million excess jobs today. Bob pointed this out and we’re three and a half percent unemployment. It’s not like when we go much higher than four and a half or 5%, My gosh, that’d be a big move. So this is not like what we saw in oh eight where you’ve got 10% unemployment. But at the end of the day, as Bob said, this is an important part of the cycle. Recessions are necessary to prune the economy of excesses. And it’s just unfortunate. But yes, how you treat people when you go through this process is indicative of whether or not you’re following the Lord.

John Coleman: And I want to pivot back to this idea of inflation and recession in a moment, which you guys are starting to talk to you. One thing I add, Bob, that I just saw today, to reaffirm this idea that you can use variable compensation reductions or comp reductions instead of layoffs, was Intel actually took that approach today where they announced 5 to 25% compensation cuts across the board, depending on seniority, which presumably helps them manage this downturn that they’re in specifically in the economy’s in without having to enact such dramatic layoffs. And that can certainly be a tool that companies utilize. I want to pick up now on this idea of recession and inflation. We talked about six months ago. At the time, inflation was running very hot and there were very few signs that we were in a recession. Now inflation is cooling and there are more signs of a potential recession or that we might be in a recession. What is your read on inflation and recession right now? What do you think is ahead for the Federal Reserve? And David, perhaps we could start with you.

David Spika: The Fed met today. We heard from Chairman Powell. He was very clear that they still have a 2% target for core inflation. We’re a long way from 2% on core inflation. Given that and given how strong the job market is, the Fed has to continue to tighten financial conditions. And one of the problems they have today is that the market is not helping them. So stocks are up eight or 9% since November and the ten year Treasury is down 72 basis points in the same period of time. That’s loosening financial conditions. The markets rallying today on the Fed’s remarks, I guess presumable because they only raised 25 basis points. Bottom line is the Fed has work to do. Chairman Powell was very clear on that. His reputation, his legacy is on the line. And the only way we can get inflation under control is by reducing consumer spending. And the only way we can reduce consumer spending on a sustainable basis is by bringing employment levels down, increasing the unemployment rate. It’s just how things work. And historically, inflation has only been tamed through recession. So we fully expect a recession at some point, maybe in the second half of this year going into next year.

Bob Dole: So I 1,000% agree with David. So let me just say a few things to emphasize that maybe a couple of different ways. I want to emphasize David’s first point. The Fed’s target is 2%. We are a long way from 2%. So if the Fed insists on 2%, I do not see, as David said, how we avoid a recession. It may be a mild one for a bunch of reasons, but avoiding a recession is really difficult now. The other path the Fed could choose is to say at some point, you know, maybe two’s not the right number, maybe three. Okay. And if we get to a three handle, say three and three quarters, they might say, oh, let’s round it down to three. And if they do that, we could have the proverbial soft landing, but their credibility will be shot. And David’s right. You don’t bring inflation down without cooling the economy, especially the labor market, which shows lots of signs of being pretty strong. So kind of the slide I’m envisioning I put together in December was 50% chance of a mild recession, 30% chance of a soft landing, 20% chance of a more average or more difficult recession. I don’t see how we avoid it. We could debate when it’s going to start, but the markets acting like, okay, maybe inflation is not a problem because we’re bringing it down. Maybe the Fed’s almost done. Maybe the economy’s okay, let me go out and buy high beta stocks. It may not have a whole lot of quality, and I’m not sure how long that can last if in fact, we are going to have a recession.

David Spika: So let me add one more thing to that. Great points, Bob. I agree completely. You might need to get two guys that argue with each other. John, Bob and I are on the same page.

This is way too friendly. Yes,.

This isn’t very entertaining is it? So maybe we’ll talk football or something later. But we have seen by virtue of Fed policy, the largest decline in the money supply as measured by M2 ever. There is no way that doesn’t have a meaningful impact on the economy, regardless of what the Fed sees as their ultimate goal. There is no way you drain that much money out of the system without it having a meaningful impact in the economy.

Bob Dole: At the risk of beating a dead horse. I want to add to that. Yes, the money supply is shrinking. The leading economic indicators have rolled over significantly. We have the most inverted yield curve in 40 years. The PMI is are almost all below 50 here and around many places around the world. And remember, the Fed raised rates, as David said earlier, at the fastest pace in U.S. history except for Paul Volcker. And we know monetary policy operates with long and unpredictable legs. So I think what the Fed did in 2022, we’re going to feel the effects of it in 2023. So it will probably both be wrong and the economy will sail forward. But I don’t see how we avoid a significant slowdown, if not a recession.

Bob Dole: When they both are wrong. But we can still be friends. Bob, how about that?

Bob Dole: I hear you. I hear you.

John Coleman: Well, let’s see if we can spark a little debate with the next one. I wanted to turn to this topic of ESG, and Bob, maybe we can start with you. You know, ESG has been this prominent trend in investment management for some time now. It’s close to a third of the assets in the world claim to be ESG in some way. And 2022 mark, one of the first years of sustained pushback against that, notably against BlackRock, which has become kind of the figurehead for the movement in many ways. And there were effectively two sets of pushback on that that were. Prominent one was for many state based institutions, saying, look, actually all that should matter is fiduciary duty. We should not take into account things that we think are unrelated to performance. And then a second set of pushback was just around the values inherent in ESG, saying that those were inherently progressive values or they were values that people disagreed with. People are of different opinions now on what the future of that holds. What is your view on ESG and how Christian should think about ESG or more broadly based values investing in their portfolio?

Bob Dole: So I think what we’re discovering is we don’t know what ESG is. It’s different for almost every investor and every money manager. And that’s why, among other reasons, we at cross mark, we never talk about ESG because we don’t know what it is. We talk about values based investing, which in our view is a subset of ESG, not a broader concept. And the standard we bring is what is God said? You know, we could talk all day about what we think and how we would like the world to look. We try to say, you know, God in his word gives us some black and he gives us some white and it gives us a lot of gray. And that’s why it gave us minds to think through and try to figure those areas out. So I think the ESG moniker is appropriately undergoing scrutiny, confusion. And look, it will take different forms. There is no ESG standard. That’s part of the problem. And so I think the debate is going to continue to rage. And a lot of people will say, let me figure out what my values are and let’s see if we can manage money that way and get rid of this broad ESG moniker. I know there’s some ESG factors that we think are great for values based investing and others where we want to actually reverse the sign. So it’s a very confusing subject, but one that we’re all trying to wrestle to the ground.

David Spika: Yeah, ESG has become a dirty word because of the association with the climate change agenda. And as Bob said, we at guide stone don’t practice ESG. We don’t want to get caught up in ESG. What we do is faith based investing. We want to invest in a way that has a positive impact on the kingdom. Only 15% of evangelical Christian investors invest in faith based investments. We want that to grow. We think that a tremendous opportunity to introduce Christians to faith based investing. We know about tithing, but they don’t really understand the opportunity or really the obligation they have to invest in a way that honors the Lord. And so there’s a big educational process that firms like cross mark and guide stone are in the process of doing and creating and going out and teaching folks about faith based investing about biblical values investing and how it’s different than ESG. And I think that’s on us to make sure Christians understand they have that opportunity.

John Coleman: Yeah, and we think the same. I think I would agree 100% with both of you. You know, the Bible actually consistently has a lot of commands about how we live our financial lives. It’s obvious that God cares about how we steward capital in the Bible and in church history. ESG is a particular set of values. Like you said, Bob, some of which are aligned with biblical values or Christian values, some of which are not. Right. And I think what’s incumbent upon us now is for us collectively to develop a more nuanced set of views about what Christian values look like manifested in a portfolio. And David, then to your point, to encourage people who are Christians to take into account their values when they’re allocating capital as much of the world already has through ESG investing, but Christians have kind of lagged behind. I think.

David Spika: Amen.

Bob Dole: As David said, it’s an educational process. I think we would all agree. Most Christians think about how they earn their money. You know, they’re not going to rob a bank every other week to put food on the table. And at the back end, how they spend their money and where they give their money, they give that thought to from the faith. But this in between that and that’s investment part. Boy, a lot of people, they’re not even aware of that possibility. So it’s a fun education process.

John Coleman: So I’m going to pivot us now from a very fine and catchy topic like ESG to a very nerdy topic like bond markets. And David, I figure you might be able to kick us off here. You know, you guys mentioned at the beginning, 1870 was an interesting statistic that I didn’t know, but bond markets absolutely got hammered last year. And for the first time in a long time on the other side, fixed income, even money markets are starting to yield again, Right, Because the Fed rates are going up. Even I now see CCD advertised, which I haven’t seen since I was a kid, probably be prominent. What is your outlook for fixed income right now and how do you think about that in an investor portfolio in 2023?

David Spika: Well, John, thank you for giving me an opportunity to explore my nerdy side. I don’t get to do that as often as I would like. But I will tell you this at guide stone we’re big fans of Bonds. Today. We have seen for the first time ever back to back negative total return years for the Barclays Act. Never seen that before. Bonds consistently produced positive returns. Today you can get four and a half percent or more in short term, high quality bonds. Think about it. Most investors, what do they want to earn? A particular retirement? 6% or so. Wow. If I get four and a half percent in the safest part of the market, that’s a great opportunity. The thing that happened last year that scared a lot of people off was the rate volatility. As the Fed was raising rates, rates were going crazy. The MOVE index, unlike the VIX, was going crazy and that had a big impact on bond prices. And I think people got scared off a little bit. But we’re near the end, close to the end, obviously, of the rate hike cycle. You’re already seeing the longer end come down for rates. That’s positive for bond investors. So you buy these bonds at some point, you get an opportunity to go further out on the yield curve, benefit from current yields that are the highest we’ve seen in 15, 20 years and benefit from the capital appreciation that will occur as rates fall when we get into weaker economic times. So we’re big fans today and think investors really need to be taking a hard look at the bond market.

Bob Dole: So, John, as you know, I’m an equity investor, so I start with the phrase bonds are boring but boring is but boring is a good thing.

John Coleman: You’re breaking David’s heart over there. I see him tearing up just a little bit.

Bob Dole: I have to disagree with him once.

David Spika: I’ve been called a lot worse, Bob, Trust me than boring.

Bob Dole: So to continue with David’s history, he’ll look back. The last hundred years I focused on the ten year Treasury. 20% of the years you lost money in a ten year Treasury, only 3% of the time Did you lose money two years in a row. Three years in a row. We went back 250 years and there are no three year rates. So I think we can take it to the bank, maybe a little strong, but close to it. That will make a couple of bucks in fixed income this year. So how do we feel about fixed income? Have some. Unlike a year ago when one and a half percent ten year treasuries, it was a place to stay away from 3.5 a whole lot more interesting. And as David said, shorter maturities, you can get four approaching five. So we want to have some. And now the question in bond portfolios having length and duration from the shortest that we ever had to more neutral, now we’re playing the credit game with fear and trepidation, but that’s part of how we’re trying to add a buffer to above the benchmarks.

John Coleman: That’s great. Well, Bob, maybe they get back on firm footing with your territory. One of the biggest hits last year was to growth stocks. You mentioned high beta stocks earlier. We saw this in private markets and growth equity and venture as well. You know, 2022 was just brutal for growth equity for growth stocks in markets, at least partially because they had gone up so aggressively over the prior 15 years and even in the last 12 to 24 months. What is your outlook for growth stocks this year and how do you think about venturing growth, equity or even public growth equity in a portfolio?

Bob Dole: So first, to extend your observation last year, to oversimplify it, but not by much long duration, things were the worst place to be. When interest rates go up, the last thing you want to own is a long duration bond. When interest rates go up, the last thing you want to own is a long duration stocks, and those stocks got absolutely pummeled. Doesn’t mean they’re bad companies, a lot of good companies. But their stocks just got crunched because the discount rate went up as as interest rates went up. So fast forward to today and then back to my observation, how much value beat growth last year. So we want some of both in our portfolio. You put a gun to my head. I think value will be growth again this year for a whole bunch of reasons. But in the portfolios I manage, I want some value. I want it to be higher quality, predictable value given the economic landscape that Dave and I just posited for this year. But I want some girls too. I just don’t want to pay ridiculous prices, so maybe growth more at a price to get some balance in my portfolio.

John Coleman: David, this is your chance to get a little revenge for that boring comment. What do you think?

David Spika: Yeah, I’m still thinking about that one, so I’m going to be a little bit off the Bob train. We like growth and let me tell you why. Growth stocks, as Bob very articulately described, do better in a stable to falling interest rate environment because they’re longer duration assets. We believe we’re going to have a stable to falling interest rate environment this year. Secondly, investors pay up for growth when growth becomes scarce. And we believe that the economy is going to slow down earnings. Growth has already started to slow down. Growth will become scarce, so investors will pay out for growth. And finally, for long term investors, which I hope we all are for buying equities growth companies is where you get innovation, right. And you talked about venture capital and you talked about private equity. Obviously, you’ve got to be a long term investor because you can’t even get your capital for ten or 15 years out of those. But that’s where the innovation comes in. So to have a portion of your portfolio in those types of companies is really going to benefit you longer term and give you the opportunity, invest in really exciting parts of the economy, whether it’s AI and machine learning or whatever the case may be, that you can only access through growth stocks.

John Coleman: Yeah, it’s only a matter of time before we’re just using chatGPT, I think, for this podcast. So there is a lot of excitement.

David Spika: You could get rid off Bob and I and AI is going to be making up better stuff and we have.

John Coleman: Right, they might keep you, but my job is definitely in jeopardy here. You know, Bob, maybe pivot back to you and let you start. You do these ten predictions every year that are fascinating. I’m not going to ask you for quite that many, but to almost round us out today before we come to some lessons you’re getting through scripture right now. I wanted to get each of you just to give me your three best predictions for 2023. Bob, what do you think?

Bob Dole: Because you prepped as I looked through my ten and I singled out three. If singled out means three, I don’t know. But it is. Inflation falls substantially this year but does not get down to the Fed target. So good news but not good enough news. Two earnings falls short of expectations. We talked about earnings recession earlier. You know the number for the 2023 S&P 500 peaked at over $250 a few months ago, is now in the two twenties. I’m going to get down to $200 and three. The average equity manager beats the index this year, while last year, after eight years where more than 50% of managers lagged the benchmark. I think this will be the second year in a row, and there are a whole lot of reasons when interest rates are stable, when they’ve gone up, when interest rates are more market set rather than artificially set fundamental research matters. And so that’s the third one.

David Spika: Well, John, let me give you my three. I’m going to say the Fed takes the Fed funds rate to at least 5%, Stay it to the end of the year, and that pushes the economy into recession. Secondly, I think bonds beat stocks this year. And thirdly, I’m taking the chiefs over the Eagles in the Super Bowl. Sorry, Bob.

John Coleman: There we go, we got Mahomes guy here.

David Spika: Hey, Patrick. Mahomes is my guy. Okay.

John Coleman: So I’m worried about that. I’m worried about the ankle.

John Coleman: David, He looked okay, but that ankle’s making me nervous a little bit that I’d have to pick the Chiefs as well. Bob, you’re a little surrounded at the moment

David Spika: I’m outnumbered. We’ll talk. We’ll talk two Mondays from now, guys.

David Spika: Yes, we will.

John Coleman: Well, hey, this is the Faith Driven Investor podcast and the Faith Part of that’s really important. Y’all have touched on that a bit. But we do like to just in the podcast asking each of our participants about what they’re learning from Scripture right now that they think might be relevant to others. And David, if I could start with you, just be curious. Anything in your personal devotional life that you’re learning right now that you want to share with others?

David Spika: I love this question, John. Thanks for asking. In our small group, we’ve been studying the life of David, and one of the things that really stands out about David is even though he was anointed by God to be the king of Israel, he didn’t try and force it. He didn’t try and overtake Saul. He had chances to go and take over and to kill Saul and become king. But he didn’t because God wasn’t ready for him to do that. So he showed patience, he showed humility, He showed obedience to God, and he waited until God was ready to put him in the throne. And I think that’s a great lesson for us to learn in this business, particularly in an environment like this. Let’s don’t try and get ahead of things. Let’s make sure that we’re doing what honors the Lord every day, practice that humility, practice that patience and truly honor him and do what’s in the best interest of our clients.

John Coleman: Bob, what about you? What are you learning right now?

Bob Dole: Yeah, mine’s a simple one. God is sovereign. I mean, we know that factually, and I would say experientially, I’m just grabbing a hold of that and apply it. Some of the things we’ve talked about the economy, layoffs, people are going to lose their job and that’s not fun. But, you know, God knew that was going to happen because he’s sovereign over all things, all people at all times. And so I take comfort in that on the good days in the not so good days, that we can look to him as the God who wants the best for each of us. And if we accept his sovereignty in recognizing he has our best in mind, the days get a whole lot easier to live.

John Coleman: Amen. Amen to both of you on that one. And certainly, Bob, that sense of trust and. Sense that there is someone who cares about us and that we can take a very, very long term perspective with regards to our salvation. And also how all these things are going to work out is quite comforting in times like this. This is Bob Dole, CEO of Cross Smart Global Investments. David, Speaker, President and CEO of Guide Stone Capital Management. Gentlemen, as always, incredible insights. We’re really grateful to you for sharing them and they’ve been a great benefit to us today on the Faith Driven Investor podcast. Thank you very much.

David Spika: Thank you, John. Enjoyed it.

Bob Dole: The privilege.

Subscribe to the newsletter

Stay Connected
to the Movement

We know that as an Entrepreneur, your most valuable asset is time. So each month we take the very best of the podcast, the blog and all the news, resources, and upcoming events happening across the space and bring it to you.

Episode 139 – Marks on the Markets: Are We Witness a Great Tech Reset?

Episode 145 – Marks on the Markets: The State of Faith Driven Investingnd the Bubble: Why This Could Be Venture’s Most Explosive Era Yet with Rob Go of NextView Ventures Copy

Podcast episode

Episode 145 – Marks on the Markets: The State of Faith Driven Investingnd the Bubble: Why This Could Be Venture’s Most Explosive Era Yet with Rob Go of NextView Ventures Copy

Faith Driven Investing has been around for much longer than this podcast and ministry. It is an international movement of leaders deploying capital for Kingdom impact. Our host John Coleman likes to joke that it’s been around for at least 5,000 years. But even with its rich history, there has been an obvious uptick in activity in recent years.

Today’s Marks of the Markets episode functions as a “state of the movement” with two long-time advocates and practitioners of Faith Driven Investing: Henry Kaestner and Ross Roggensack.  Check out the full episode to hear how the movement has evolved and where these leaders think it will go next.

All opinions expressed on this podcast, including the team and guests, are solely their opinions. Host and guests may maintain positions in the companies and securities discussed. This podcast is for informational purposes only and should not be relied upon as specific investment advice for any individual or organization.

Episode Transcript

Transcription is done by an AI software. While technology is an incredible tool to automate this process, there will be misspellings and typos that might accompany it. Please keep that in mind as you work through it.

John Coleman: Welcome back to the Faith Driven Investor podcast. This is John Coleman and this is our monthly marks on the Markets episode. However, we have a unique twist on marks on the markets this month. Typically, we just check in on the state of markets, some of the underlying dynamics in financial markets. But today is a very special episode on the state of faith driven investing here at the beginning of 2023. And we have two very special guests as a result. First off, is a longtime friend of Faith Driven Investor, as well as a leader in the faith driven investing movement, Ross Roggensack, who’s the founder and CEO of Oak City Consulting, which advises institutions, religiously aligned institutions on how to allocate their capital and invest both for performance as well as for faith integration. And then we have on the other side of the podcast, mic today taking a step away from Faith Driven Entrepreneur Henry Kaestner, the founder of Faith Driven Investor, founder of Faith Driven Entrepreneur, founder of Sovereign’s Capital and Bandwidth and a longtime leader in the faith driven investing movement. Ros Henry, it’s so great to have you all on today.

Ross Roggensack: Thank you.

Henry Kaestner: What a great treat. Its co-founder. I love that you’re making me sound so important. Special this morning. It makes me feel good. And yet it is the case that there are some amazing people around that have been instrumental in starting Faith Driven Entrepreneur and Faith Driven Investor. And when I think about people who have gotten this movement from the beginning, I can’t thank much beyond Ross Roggensack, I get to know Ross maybe a decade ago or so, which feels like a century ago in dog years in terms of the movement. But for me to be doing this podcast with both of you is really special. Thank you. Thanks for having me.

Ross Roggensack: Yeah me too hear here.

John Coleman: Well, Henry, I want to tee up right where you just started. You and Ross have been longtime leaders in the faith driven investing movement. Give us a little bit of that history for listeners who are unfamiliar, both of you, I’d love to hear how you got started in faith driven investing and what got you motivated to get involved.

Henry Kaestner: Yeah, maybe I’ll go first, Ross and then you pile on, please. So from my perspective, my experience is that I was an entrepreneur and worked on Wall Street, came to North Carolina in 1998, came to faith, most importantly, and then together with David Morgan, started bandwith. I had a company based on the foundational values of faith first and family, then worked in fitness and got six, seven years into it. Dave and I realized that through the grace of God and despite making a lot of mistakes along the way, we were able, through God’s providence to be a witness to His love for us and endeavor to run the business a bit differently and and saw, of course, how business can be used as a means for sharing Christ’s love, making a redemptive product and service, doing things differently. And the question was, well, what might we do outside of Bandwidth to encourage more of that with others we’d met and the idea was maybe we’d go ahead and start a fund. So that was the beginning of Sovereign’s Capital six years in, maybe we realized that we were say no to most of the companies who are coming to us for financing. And since we got into the business because we wanted to be an encouragement to faith driven entrepreneurs, if you say no 99 out of 100 times, not really being an encouragement to them. So we started the ministry called Faith Driven Entrepreneur then, and Faith Driven Entrepreneur is known for a content and community blog, podcast conference, monthly groups. But two years in to that, I got a call from a guy from Uganda and he said, Listen, I actually Rwanda. Sorry, he said, I’d really like for you to invest in my business? I said, Well, we can’t because we don’t invest in Africa, but we’ve got this other ministry. I realized that in talking to him, while he appreciated the different offerings that we had at Faith Driven Entrepreneur, we really weren’t scratching his head. He was still, at the end of day, he’s still looking for investment capital. And we decided then that we would start a ministry called Faith Driven Investor on one hand, Yes, to help some of these entrepreneurs from around the world to find like minded capital. But then more broadly, what might it look like to encourage the development of a larger movement of faith driven investing, especially in private markets, especially in [….] to be clear, there had been a lot of work done for a long time in lots of different sectors of investing, particularly in public markets. But not a lot had been done on the outside. And so we felt led to start Faith Driven Investor as a complement to Faith Driven Entrepreneur. And it was gosh, four and a half, five years ago I think we got together with Ross in Park City, Utah, to talk about what it might look like to create a movement or almost an industry trade group, but really, really a movement, just men and women coming together that were stewarding institutional capital. How might, we’re motivated by our Christian faith, allocate that capital in a way that might honor God. How might we encourage faith driven entrepreneurs? How might we encourage the thoughtful deployment of capital in segments like real estate and all sorts of different asset classes? But it’s been unbelievable over the course of the last five years how much supply there now is across virtually every asset class. Dozens of players in the space on the supply side with excellent track records. It’s unbelievable. And there are hundreds and hundreds of families that are looking to deploy their capital consistent with their faith. Thousands, really, and dozens and dozens of institutions that are getting really, really serious about it, too. So it’s been a beautiful run. But I’m eager to hear about Ross’s background because I’ve seen Ross and I can’t, I can tell you this is a means to further introduce Ross. I can’t think of another individual that has got in this space of faith driven investing more than Ross. Ross How that become the case.

Ross Roggensack: Oh, my goodness. That’s so scary to walk into that area, but I’ll try. I started in the business in 1989 as a stockbroker, very traditional, you know, broker dealer selling Cracker Barrel stock. And Ginnie made collateralized bonds to anybody who would answer the phone and just kind of just dragged along until one day I was just pulled into a Christian foundation who needed help. And really, it was just I think the Lord just dragged me in. It really wasn’t any sort of a grand master plan. I wish I could say it was, but it wasn’t. And that was back when I was at a wirehouse on a team. A great team. Still love those people and still loved working there. But in 1999, I came to know the Lord. He captured me on a rooftop on a mission trip in Mexico. It’s a long story. I won’t tell it. But he gripped me and shook me and it took me a while. But finally, in 09, after the crash, after a lot of things revealed themselves to each other, I just decided it was time for me to go off on my own and to live out my faith in a way where we could serve only Christian institutions. So we really don’t do any financial planning. We don’t help people save for a beach house, We don’t do retirement planning. All we do is work with faith led Christian institutions to try to help them invest capital. And so that’s all that we do. The kind of the start of it was really you know, I’m a hockey fan. I love to watch hockey, and I’m always muttering under my breath when I’m watching my team play, like shoot the puck, shoot it, shoot the puck, because you can’t you know, you can’t make a shot, you don’t take. And so we just shot a lot of pucks, you know, we just tried a lot of stuff and some of it looked right or felt right but wasn’t right. Some of it we couldn’t quite tell what we were doing, but it just took a while until we finally, I think, started finding things, found us, and now I think we have a pretty good handle on what we’re trying to do to help institutions do different things. You know, you’re not going to look any different if you do everything the same. So we try to encourage institutions that are faith led to allow themselves to be faith led, you know, allow it to happen.

John Coleman: When you both talked through your legacy in the area and I like to joke with people, you know, Faith Driven Investor thing is at least 5000 years old if you think about the history of Judaism. But it does seem to have accelerated quite a lot over the last decade since you got in Ross In 2009. Henry Since you founded Sovereign’s Capital in 2012, what has changed and what are you most excited about here at the beginning of 2023? And maybe, Ross, we can start with you.

Ross Roggensack: Well, I mean, maybe part of it is my own understanding of what it is when you think about what is it me preaching to the choir. Now I’m looking at Faith Driven Entrepreneur on the screen. When I think about what’s faith driven, what is faith, you know, and faith is action. Faith is when the woman touches Jesus’s garment. You know, nothing really happened until she did that and nothing really happened until Abraham took Isaac up on the altar and began to sacrifice him. You know, that was action. And so I think for me, what’s changed is that we’re becoming more active and we’re seeing more action, which is faith. Right. And it’s fun to watch people who are stepping out in faith, people that have real investment chops, you know, people that are leaving Goldman and leaving big firms, smart firms that are saying, I want to do this. You know, I think about Victor Hu, people like that that just they could make a killing. Right. If they just stuck right where they were. But they are acting on their faith, their faith driven and they’re moving. And it’s just so fun to find them and to watch them. And I make the correlation that when my girls were growing up, which was a long time ago because I’m old, but we started to try to find Christian music for them to listen to. And trust me, in the year 2000 or so, it was Sandi, Patty and Michael W Smith, and that was it. And so it wasn’t that encouraging to find music for them to listen to. But as time grew, as the movement grew, you know, there’s now there’s lots of high quality options to choose from. And it kind of feels like we’re getting there on the investment side. There’s we’re not conceding all the time or dreaming. We’re finding stuff. It’s great. So I might have gone on too long. Sorry.

John Coleman: No, the only objection I have is in 1990s kid, Ross’s the notable exclusion of bands like Jars of Clay and Audio Adrenaline from the 1987.

Ross Roggensack: That was on purpose John.

John Coleman: Music. But Henry, what about you? You’ve been in for a decade now really thinking about this consciously. What’s changed and how do you feel about the current state of the movement?

Henry Kaestner: Oh, so much has changed. So many things to point to. I think about selection and entrance in the space. I think about professional fund managers getting together to encourage and worship God together. I think about what’s going on overseas. So those are three broad categories. Maybe we don’t [….] all in the same question. So maybe I’ll just hit the selection first. You know, when we started, it really wasn’t a whole lot going on in the private and the alt space. There was quite a bit of work done on the negative screen space, which is let’s not invest in companies that might advocate for adult entertainment, abortifacients. A whole bunch of different things had been around for a while, and yet this concept of Christ followers would be knowing what they’re for rather than just what we’re against wasn’t really built out at all. And especially, again, not in the old space. You fast forward though, five years on and it’s really amazing what’s out there. So I’d put that in three broad categories. One is I’d say that there are fund managers that existed that we just didn’t know about five years ago, and I think quite a bit quite a few of them are on the real estate side, multifamily ten or 15 years ago, Apartment Life, which is a great ministry out of Dallas, started partnering with Secular fund managers and Christian fund managers. But to put apartment chaplains in place in communities where there are a couple hundred spaces, finding that by doing so that they were decreasing the turnover, which means increasing the profits of these multifamily apartment holdings. And so I didn’t even know that that existed. I think back to the way we were investing funds out of our family office. We had a lot of real estate investments, but we didn’t have any. And these fund managers, I just didn’t know they existed. Well, we know that they exist now and there are dozens of them, and it really is amazing. I love this is one of the things I think needs to characterize the movement is that you get better returns when you love on the people that live in your properties. And that was really neat. That was a bit of revelation. And the next one is funds that has started over the course the last five years. So Ross mentioned one of them. Victor Hu left Goldman Sachs. He had started the education technology practice at Goldman, was there for a decade left and with Goldman Sachs as his largest LP started Lumos Capital to invest consistent with his faith with a chaplain on board. So what is consistent with your faith mean, well, it can mean a lot of different things in this movement. A faith driven investing is not meant to be prescriptive or presumptuous. It’s got to be X, Y, and Z. It is, however, about us getting down on our knees and asking God, how would you have us deploy the capital you’ve entrusted with? An outcome for somebody might be to invest in solar farms in the divided desert because you’re called to creation care for somebody else who might be investing in Faith driven entrepreneurs in Africa. There’s no right answer other than the process by which we ask God how we might steward the capital that He’s entrusted us with. So you’ve got people like in this case, though, with Victor, he sees an opportunity to love on these entrepreneurs that are really setting themselves out there. You know, they’ve delivered a hockey stick type of projection in their PowerPoint presentation. There’s a lot of stress in being an entrepreneur as you try to deliver on what you promise. You’re trying to do a good job of leading your family in your community, in your company, and you’re always selling something to somebody, you are selling something to your customers, your employees to come on board or sometimes your employees to stay. You come home from work and your spouse says, Honey, how is it at work today? And and they’re like, Well, it is great. And because your spouse thinks he knows you left a great job, you headed IBM or fill in the blank. Right? And so Victor realized that he had an opportunity to really love on these portfolio CEOs. So to be able to offer chaplaincy up in an anonymous way in an environment where mental illness is five X among entrepreneurs, suicide rates are two X among entrepreneurs is doing a countercultural thing by saying, you know what? There is an opportunity to be able to have a chaplain in place and gosh it is amazing. If you think about [….] Wang, who left Warburg Pincus to get a $575 million fund. Zuckerberg Chan, one of his largest LPs, excellent health care investing. So a whole bunch of funds that have been started with people who have come into this space, having had great track record, so important that this movement is characterized by excellence. And I think of dozens of funds like that. And then maybe my favorite section of funds are the funds that have been recast, reinvented, if you will, in light of the Faith Driven Investor movement. A good example. There’s good water capital, good water with more than $3 billion under management, a great consumer technology venture capitalist [….] Chen, Eric Kim, guys who invest in some of the biggest names ever [….] was the first institutional investor in Facebook way back when. And these guys got together and said, You know what, We started our fund eight years ago. We knew we were serious about our Christian faith but didn’t really know what that meant. And what’s not really clear that our portfolio and what that meant or our employees. And so we’re going to go ahead and have a little bit of a restart. We’re going to go ahead and recast our fund in light of Micah six eight. We’ll let everybody know and I’m going to go ahead and take Dave Gibbons, one of the most popular pastors and speakers on Christian faith in the marketplace out here on the West Coast, going to have Dave Gibbons be our corporate chaplain so that we can be intentional about how we bring God’s love into the work we do. And so, gosh, that’s one area. Maybe we’ll talk about some of the other things going on in other places later, but that’s a big development that none of that happened aside from some of those real estate funds I mentioned. But five years ago it looked a lot different.

John Coleman: Yeah, and that was one of the surprising things for me when I came out of mainstream asset management a couple of years ago and joined sovereigns, Henry was just, I did have questions. We did joke about the Christian music problem. Ross And just if we were going to do this, we had to do it really well, right? If we were going to do this, that all the faith driven products needed to be at least as good as their mainstream counterparts. And we thought that that was possible because being faith driven, abiding by those values actually created the kind of cultures that could outperforming companies or in real estate developments and hopefully serve both the interests of investors for whom you’re a fiduciary as well as the kingdom through faith align impact. And I’ve just been continuously surprised by the breadth of different offerings that are out there and continue to believe that there’s almost no asset class where you can’t have some sort of faith driven impact. I’m sure there are a few we can snipe over time, maybe gold commodities or treasuries or something like that. But it feels like most of your portfolio can get there. Before we dive into portfolio construction, I want to pick up with you, Ross, on a thread that Henry mentioned and then get both of you to weigh in. Henry had mentioned not just the managers, which we’ve just talked about a bit, but also the community. Talk to us a little bit about how you’ve seen the community around faith driven investing broaden and get more active. I know, Ross, you hosts parts of that community at various times. Henry you do as well. Ross what’s happened to that small community of Faith Driven Investor over time?

Ross Roggensack: I think it’s growing. It feels like it’s growing. COVID was certainly a, you know, slowed everybody down in terms of momentum. So it was a little hard to gauge where people are at. I kind of feel like more and more are understanding it, but yet there are many that don’t. And we kind of joke in our shop kind of sometimes we meet with potential clients and you can just tell they’re not engaging. And it’s more a matter of just shaking the dust off and going to the next one instead of trying to coerce or convince someone. I think you either you either grab this or it grabs you or it just passes you by. And so we are more and more satisfied that the Lord will just lead us to people that want to do this, that embrace this, that are looking for ways to do this, to activate and engage their faith in the way that they actually invest money. So I think it’s growing. It feels like it is it’s moving past the negative screening into the positive impact. I think ESG has had a great influence on us, not that we’re becoming ESG investors, but I think we’ve sat back and watched ESG and thought, Oh, I’m wonder if we could do that on our side now. And I think a lot of us and a lot of that talent that Henry was talking about has seen the same thing. And probably thought, man, if they can do that on the social governance side, surely on the faith driven side, we can do it. And so I think it’s growing. I feel like it is. You know, there are moments of discouragement for all of us, but there also are moments of great joy when we get to connect with somebody who says, yeah, let’s go for this, or we engage a new client that two years later says, This is even better than what I expected it to be like this.

John Coleman: I agree Ross.

Ross Roggensack: more joyful than where I thought it would be.

John Coleman: I think the ESG movement in particular has woken people up to the idea that they can invest according to their values and that there are a set of Christian values that are not necessarily running totally contrary to those expressed in ESG, but are probably distinct from those in that there’s an opportunity for Christians to identify those values that they want to see expressed in capital specifically. I mean, Henry, you’ve created two of the biggest ministries in this space, and especially with Faith Driven Investor, you’ve co-founded a ministry that’s seeking to expand the community here domestically and internationally. Talk to us about what you’re seeing on the community side.

Henry Kaestner: Well, I think it’s exploding. I mean, I think it’s I’ll tell you some of the things we’ve seen. So we decided the hallmark to the Faith Driven Entrepreneur ministry over the last two years has been groups, groups of faith driven entrepreneurs to get together and look at content, community gather. So we have just great storytelling mini documentaries coupled with teaching from a guy named J.D. Greer, and it’s groups of 12 or 15 entrepreneurs getting together over eight weeks and then every month going forward and these different types of groups. And we’ve been really, really encouraged by the growth of them. We now have more than 10,000 entrepreneurs that have gone through groups all around the world. So huge growth that we decided based on the success we’d seen with content and community, that we would go ahead and create a beta product to see if we could do something on Faith Driven Investor. So we put together some content from some friends of the movement. We had Tim Keller do a talk for us on the identity of an investor. Andy Crouch on one on God and Mammon. Greg Lernihan on the framework of how to actually go ahead and deploy capital consist with Faith Driven Investor and had 650 folks go through a beta last year and total and we had 400 go through just this most recent nine week cohort. And so it just is growing. So we’re going we’re doing 400 a quarter over the course of this coming year. And we decided that we might take some of those that are going through these groups that are institutional investors. You don’t need to be an institutional investor to go through a group, just need to be an investor. And we tend to bring together groups of accredited investors and groups of peers coming together. We have groups for advisors, but we had some of my friend I live in Silicon Valley, so I’ve got some good friends of mine that are Christian, that are in venture capital. So I had some of them go through a couple of groups that I led, and we decided to do a reunion of sorts out at the Rosewood Hotel out here in Palo Alto. And long story short, we had 164 Christian general partners of venture capital funds and private equity funds at the Rosewood Hotel three weeks ago. And these are people from Andreessen Horowitz from Madrona, Good Water, as we talked about some of the biggest names in the world of private equity venture capital. Most of these in secular funds, but all of them very committed to their Christian faith. And how is it manifests itself at their otherwise secular fund? How does it manifest itself as they work with secular CEOs of portfolio companies? What does that look like? How can we praise God together? How can we pray together? How can we share what God has done in our life together? And this is the first time that most of these folks had ever gathered with other Christians in their profession. And yet there is 164 of them. And then ten days later, we did the same thing in Nairobi, where we had 55 Christian fund managers getting together. And these are I don’t know what the audience is thinking of right now in terms of what a an African fund manager looks like or does or invest in. But we’re talking about people like Richard Okello came out of Bridgewater. He was a partner with Ray Dalio. He’s running just about $400 million in a fund of funds out of Johannesburg, South Africa. Top tier, you know, […] who I met when he was at Wharton, running a couple hundred million dollars, investing in Africa. You know, we’re talking about a continent with greater GDP growth than any other continent in the world and with the demographics. So I could talk about Africa forever. I think it’s amazing. But 55 of these Christians, all of whom are fund managers, getting together to worship together and say, gosh, what does it look like in light of ESG, in light of where God has us to come together and community and to encourage and challenge each other as we allocate capital? And then and to be clear, they’re fiduciary. So they’re not all themselves just investing in faith driven entrepreneurs, though some are. But how do we recognize that God has placed us where he has not just to make a ton of money for our clients or for ourselves, but to be his hands and feet and to be a blessing in the market place, what does that look like? So I’m extraordinarily encouraged by the uptake. And then we’ve had thousands of families come in through the Faith Driven Investor website to go to the marketplace to say who are some of the funds that are out there? And then increasingly, the big question is knowing that we have the supply now and we have the demand. Who are the fund advisors? Who are the river guides out there? They kind of know how to make this happen, understand a family’s need for income or interest in a market or an investment class, and put that together. And that’s what we’re focusing on most in the movement over the course of the coming year. How do we help fund advisors who are, you know, back to Ross in the hockey thing, who understand where the puck is going and seeing that Christian families, Christian institutions are going to get more excited about participating in this space. How do we help them come along, particularly with individual families?

John Coleman: Yes.

Henry Kaestner: Because alts have been difficult for many individual families and then Faith Driven investing has been difficult. But Ross has done such a good job to position himself as this institutional fund advisor that Ross, my prediction is that this is going to be very good year for you.

John Coleman: Well, and Henry to pile on that, I think another question I had coming into the space a couple of years ago is how our clients going to find these products, right? Because almost everything in investing happens through an intermediary like Oak City Ross. And it is encouraging. I mean, Ross is stewarding capital through Oak city for institutions. There are big wealth managers like Ronald Blue Trust and Eversource that are now explicitly serving faith driven communities. We’re seeing firms like LPL develop model portfolios for faith driven investors. I think they have 1000 kingdom advisors now on the LPL platform, and we’ve even seen big firms like NCF recently introduced faith aligned model portfolios for its investments through its donor advice funds. And so a lot of these intermediaries by which individuals or institutions access the market are becoming a lot more open to faith driven investing, even if they are mainstream institutions like LPL. And I think the call to action we probably have for anyone out there is if you’re getting advice, seek out someone who’s going to offer you these options like Ross or lobby the place that you’re at to try and introduce those. I know we’ve got a lot of active discussions going through FDI, through sovereigns and others with big firms that are seeking to serve their Christian clients better. And a part of that is introducing them to the ideas of faith driven investing. Ross, one thing I wanted to dig in on, because you’ve got such a good view of this from where you set your advising a number of different clients with complicated portfolios. You’ve both talked about how we’ve drifted away from just negative screening into some sort of positive engagement, and we hear a lot of frameworks [….] around. We hear avoid, embrace, engage, for example, there are some other frameworks out there. Ross as you think about faith driven investing in 2023, what framework are you introducing to clients to understand that?

Ross Roggensack: Well, we’ve used the framework of redemptive institutional investing, and it sort of stands on four pillars, one being that ownership, that God owns it all, that it’s not ours, that we’re just stewards, we’re just managing it for him, for the ultimate manager. The second pillar is design, that our design is not nearly as good as his, that we need to get under his authority and under his design. Third is that capital has influence. So directed institutional capital towards a cause, towards a movement, can influence culture, can influence living conditions, can influence medicine, can influence housing, can influence clean water, whatever you want, but money can change things. And then last excellence matters that everything we do in word or deed, right? Everything is unto the Lord. And so we should do it really well. We should really focus not on just providing product, but on really solving the problems, both on the investing side and the impact side for institutions. So we call it redemptive institutional investing, avoid, embrace, engage. It’s fine too there’s lots of different monikers. But yeah, we especially believe that that institutional capital, when directed collectively, can really change the world. And again, back to ESG, we’ve seen it change the world some good, some not so good. But we think once especially larger institutions can understand this and grab it, we will, in our day, see change and it will be so great, now I am seeing some. But I’m really anxious to see more.

John Coleman: It’s super encouraging. Ross and I want to zero in your fourth pillar was excellence, and both of you have talked about that a bit. You know, Ross, you’re stewarding client money every day. Henry. You’ve stewarded your own capital as well as the capital of others in a way that’s almost entirely faith aligned for some time. We’ve talked about how important it is that these faith driven investments perform at or above market, at least some of them. Some of them might be concessionary, but many of them you’d want to perform at or above market. Are we seeing that excellence materialize? Henry? Are you able to get the same types of returns in faith driven investments that you can get in mainstream investments today?

Henry Kaestner: Absolutely. So five years ago, I came back from this conference we had in Park City and realized that aside from sovereigns and the stock I had in Bandwidth and Republic, I didn’t have any Faith Driven Investment. And so I thought that’s that’s a challenge. We had lots of secular fund managers because venture capital and real estate and so decided to put together a portfolio just of Faith Driven Investor across pretty much every asset class. And we hired of course in Kenny you’re now works at sovereigns to do that for us. And over the course of two and a half years, you put together a portfolio and gosh. Maybe we’ve got 35 fund managers now that have some level of spiritual integration or written spiritual integration plan to talk about how they want to steward capital. And that goes across the spectrum. And you alluded to this just a second ago, and that is that faith driven investing doesn’t just include market return capital, but really what we look at Faith Driven Investor is it includes a spectrum from market return capital through to patient or concessionary capital, where it’s the outcome that’s most important, not the return that’s much more. With market return capital, the outcome, the return is the most important. Now it’s table stakes. It needs to have some spiritual integration in it. And yet there are lots of opportunities, particularly in frontier and emerging markets, where the outcome can be the most important, where maybe it’s employment or it can be the end of disease. And yet it’s not philanthropy, which we’ll talk about in a second. The best way to accomplish that intervention is through investing in innovation. And yet, in order to get the best maximum outcome, you might sacrifice some return. Maybe that’s because of currency, maybe that’s because of a long term investment in R&D. Whole bunch of different reasons that could be. And then on the other side, of course, there’s philanthropy, all of that. I think that God, well God owns it all. In all, three of those tools are at disposal to be able to be faithful and obedient with number one, understand he owns it all. But then to experience the joy is another thing I want to make sure that our listeners here hear is that we’re talking about an investment strategy that isn’t just born out of faithfulness and obedience, and we’re going to take up our cross and we have to die to self. And all those things are true in Scripture. And yet I think with faith driven investing, God’s calling us into something much greater. It’s a Technicolor existence, a participate in the work that he’s doing in the world and experiencing his joy. But back to your point. Absolutely. Market return is a big, big, big piece of that. And we have found over the course of last five years that our market return investments that we classify as such when we invest in it, when the manager says I seek to meet or exceed that of the secular benchmarks and private equity could be endeavoring to be a top quartile fund, we found that those investments have done better than their secular alternatives. And so about, gosh, in the family office, maybe 50% of the funds that we run are just market return and they have outperformed their secular counterparts.

John Coleman: That’s hugely encouraging. Henry And I know through Faith Driven Investor you actually help make available the holdings in that portfolio and things like that. And so that’s something that others can dig into based on the research that you, Henry, are doing or you’re doing. Ross As you think about and Ross, I want to turn to you obviously were pursuing excellence. There are some strategies that end up being more concessionary, but we’re pursuing excellence. We’ve talked about a number of categories that are being built out. So public equities, negative screening has been around for quite some time. Henry You mentioned 164 GP’s from private equity and venture firms dominantly gathering recently in the explosion of those funds. Where are you seeing gaps in a Faith Driven Investor portfolio right now and where are there asset classes that we need to further innovate to make excellent within faith driven investing? And Ross, maybe kick us off, if you would.

Ross Roggensack: That’s hard. I think that for us we’ve had a real focus on real assets and whether that be oil and gas, farmland, you know, even water. It feels like there’s been some gaps there for us to be able to really bring a a redemptive faith led offering there, you know, growing food, growing it wisely. Protecting the environment are all really important things and they’re redemptive in nature and they promote human flourishing for sure. But to be specifically faith driven, not sure there’s a lot really offered outside of the real estate portion that Henry mentioned. In real assets, I don’t see a lot, but Henry probably sees a lot more than I do there, there is probably a little bit of a gap. I wish there were more offerings in medicine. I don’t see enough there. I wish there were more because I really think that’s an area where we can really have great impact if we harness institutional capital towards that, I think we could really make a difference in drug pricing in lots of different ways that we could affect the marketplace. So those are probably two areas.

John Coleman: Henry, what do you seeing?

Henry Kaestner: Let me just say, I just love the fact that Ross used the word medicine. You know, it’s so many institutional investing conversation and everybody’s talking about pharmaceuticals. When I talk to my wife about needing something, I say, don’t get a pharmaceutical firm. They’re going to give me a medicine. I need medicine. And that’s what we need in America and that’s what we need overseas, which is where I think I’m brought to in terms of the way I think about gaps. And I suppose you could say that there are gaps in a bunch of different places. I remember actually thinking a guy called me up, said, I want to talk to you about this fund that we’ve got and putting together a spiritual integration plan for oil and natural gas. I’m like, How do you do that? I mean, you know, how are you sharing your faith with a barrel of oil or something like that and say that, thank goodness, Because he then talked about an incredible search integration plan about being able to provide ministry to the roughnecks out in the West, Texas, oil fields in the back and oil fields in North Dakota, and really, really impressive. We had a guy on the Faith Driven Investor podcast three or four years ago, Jimmy Song talking about Thank God for Bitcoin. I don’t know that I completely get that yet. Maybe that’s just a function I’m not smart enough to follow, but I don’t know that there are huge gaps. I’ll tell you, there’s a gap though, that I see in the way that faith driven investors are looking to deploy capital. I don’t think that we generally are looking at Africa or frontier emerging markets the way we could, and yet there are some really good fund managers there. I alluded to it a little bit before, but I think it’s important that we as Christ followers look differently at risk. The traditional mindset, and I’ll speak from the perspective of a family office for a second, the traditional mindset has been really that we want to make as much money as we possibly can and to just take whatever pile of money we have and to grow it. Now, if we’re Christians, maybe we think about it a little differently. But you know, if we’re looking to grow that, to what end are we investing our capital, especially if it’s excess capital? Now, to be clear, college planning, retirement planning are incredibly important, and I don’t want to minimize that. And that is the primary need for the vast majority numbers of Americans. And yet there are quite a few family offices that have excess capital, and they’re managing excess capital and they’re looking to get better return. But to what end is it to spend more? Is it to save, to build up for the next generation more? Maybe it’s to give more of its give more. I would challenge us all to think about how we might actually place an investment capital now in a way that maybe philanthropy is not as needed in ten years. So say we want to go ahead. See, I think that you can make a really good case that investing in Africa makes a lot of sense. Right now, you’ve got GDP per capita growing faster than any other continent out there. You’ve got an age of political stability unlike the continent’s ever seen before. Demographics are a huge issue. You know, you have these bulges of population. They’re going to be producing and consuming because the average age in Africa is so young, more entrants in their marketplace in Africa than any other content coming up. I mean, there’s lots of different reasons to invest in Africa, but say you can make the case that you could get a better risk adjusted return by investing in America, and maybe you could make that case. But again, to what end? If it’s to give money to Africa in ten years, we should rethink that. Mm hmm. Philanthropy has not done very well in Africa. Not to say it doesn’t still play an important role. Philanthropy is not dead. We need to be able to give to people who are in need of relief after floods and all sorts of different issues. We need to be able to give into some of the education infrastructure that’s out there. There’s a whole bunch of reasons for philanthropy. And yet if we’re actually invest and there are some incredible funds run with excellence in Africa right now that 99.9% of Americans don’t even know about aren’t even investing. And if we can invest, maybe in investing in job creation, economic development and market forces now toward innovation, especially what’s going on in fintech in Africa, leapfrogging over what we otherwise see in developing economies. Maybe if we invest it now in job creation, maybe you don’t need our philanthropy in ten years.

John Coleman: Before we conclude today, I wanted to kind of circle back to the broad topic of faith driven investing and in kind of 30 or 60 seconds or less, I wanted to hit two questions. The first. What are your big predictions for FDI in 2023? Ross, What do you think you might see this year that’s different for FDI?

Ross Roggensack: Oh. Not sure about different. I know that in 22, biotechnology did very, very poorly. And our firm, we think in five and ten year increments. So we don’t really try to think in one year predictions. But I do think medicine and biotechnology specifically are huge themes for us. And we still believe there’s going to be breakthroughs, maybe even because of COVID, because of the money that was generated. But I think that we’ll see. I think we’re going to see great breakthroughs in medicine, especially in biotechnology this year.

John Coleman: Henry, what’s your prediction for 2023 in FDI?

Henry Kaestner: I think the biggest opportunity out there is investing in lower and middle markets. When you can get in and partner with some really great companies that are making profits right now and get in and attract the multiples, I think we’re going to see a little bit of a cooling with some of the high fliers in the technology sector and venture capital. Venture capital remains a great place for faith driven investors to look at or with a long term horizon. Short term, just incredible opportunities in lower and middle markets.

John Coleman: All right, last question and then I’m going to ask you all to just give us a verse that you’ve been meditating on recently or something you’ve learned from scripture. Very quickly, a lot of folks are on the sidelines right now, or they’ve relegated Faith Driven Investor thing to a small impact bucket in the larger portfolio that they have. What’s your advice to someone who just wants to get in the game Ross?

Ross Roggensack: Well, I guess my advice would be much like the woman who touches the garment. Like I mentioned before, I think just act on your faith. If you want to be faith led, then move yourself to action. And I don’t think the Lord is going to bless the performance, but he’s certainly going to bless us if we act. And so don’t be afraid. You know, just move, act, act in faith. And I think that just too many people have bought into the lie that it doesn’t work. And I think that people just need to act.

Henry Kaestner: Jon, knowing that your last question is going to be about what is God teaching us through his word, I’ll combine the two answers into one and then maybe you’ll finish with Ross with asking what he’s hearing from God in his Word. So for me, the thing that’s really been sobering as I go back through the Old Testament is the lessons from the Good Kings of Judah. Of course, in the bad kings of Judah. Well, don’t do what the bad kings of Judah did. But interestingly, you know, don’t do what the […..] share of the Good Kings of Judah did as well, which is that just about every one of them didn’t ask God before they went off into battle or did a trade deal. And these are men that had great common sense, were godly people. They were men after God’s heart, Scripture tells us. And yet, at a critical venture, they didn’t seek God. And so that’s a sobering lesson for me. I think back over the last year about how many decisions I made without seeking God first. And I want to endeavor to do that. And so absolutely, as I look to allocate his capital, I got to get down on my knees. I guess I got to ask, God, what would you have me do practically that would be the most important thing, followed by looking to find a good river guide. There are lots of different options now, and that’s the good news. But it does present a little bit more of a challenge. What is the right strategy for the pool of capital that you’ve been asked to steward? And we’re not meant to do this alone. So finding a good river guide.

John Coleman: Yeah. Ross Henry’s right. He introduced this question and knew it was coming. And we try and conclude every podcast with just what God is teaching you through scripture that you want to share right now. Any thoughts on your end?

Ross Roggensack: Well, I meditate often on first Timothy six two, which is a verse that means a lot to me. It basically is Paul is really encouraging us to. It says rather, they must serve all the better since those who benefit by their good service are believers in beloved. If we are serving fellow believers, I think it’s required of us that we should serve. It says all the better that people should not do this expecting Christian results that they should expect for us to serve them even better because they’re believers and beloved. And so I think that what we do can really have great impact because the Lord’s with us and because he expects us to do it all the better. So, yeah, I think that Paul’s words really ring in my ears often to really serve all the better.

John Coleman: What an awesome way to conclude the podcast. Ross. Ross. Henry, Very grateful for you all. As a relative newcomer to the space, I’m still learning at the feet of giants here like you too. Ross You’re certainly conducting a great ministry through your work at Oak City.

Ross Roggensack: I’m just old John I am just old John

John Coleman: Appearances wise, weathered and wise. And Henry, of course, deeply grateful to be your partner, business partner, as well as to see the ministries at FDE FDI flourishing. And we’re grateful to you all for your leadership in the space. Thank you for coming on the FDI podcast today.

Ross Roggensack: Thank you, John.

Henry Kaestner: John, thanks for your leadership. Great doing with you guys. Thanks Ross.

Ross Roggensack: You bet.

Subscribe to the newsletter

Stay Connected
to the Movement

We know that as an Entrepreneur, your most valuable asset is time. So each month we take the very best of the podcast, the blog and all the news, resources, and upcoming events happening across the space and bring it to you.